The Absolute ‘Must-Do’s of Payday Loans

by Magical Penny on April 26, 2012

I was reading a blog of one of my friends the other day and in his latest post he had admitted to using one of the payday loan providers loan to pay a bill.

I was really surprised because he had a well-paid job and from the conversations I’d had with him, and from reading his blog, I knew he was a smart guy. We had even got to know each other in a personal finance forum that taught good money management techniques!

I was surprised, yes, but while payday loans often get a bad reputation, I had to admit they are a great solution for a certain person in a certain situation. If you find yourself in need of cash immediately you can take out the amount that you need, use it and pay it back with your next paycheque.


But it’s really important not to get caught in the trap of using this as a consistent way to make ends meet when you don’t have the cash you need.

cautionCheck Your Reasons for Getting the Loan

Here are a few rules to keep in mind as you consider the use of payday loans. For more information on payday loans and other financial products, check out Money Supermarket.

Payday loans are for emergencies. When everything in on the line and you know that there will be real consequences if you don’t have the cash, it is time to check out a payday lender. If you find yourself consistently requesting money and paying it back later, look at some other long-term options that could be more helpful including budgeting or a credit card. Considering other options available, this is a costly way to borrow money. The fees alone make this an emergency situation only option.

Don’t Overextend Yourself

You are in an emergency and you need cash, so how much should you borrow? You don’t want to overextend yourself financially. Take out only what you need and only what you are going to be able to pay back. It can be tempting to see this as a credit line that you can borrow against but remember that there are fees associated with the loan. Get only what you need to keep your costs down.

Pay the Money Back as Soon as Possible

Unlike a credit card, you don’t have much time to pay back the payday loan. In most situations, you have two weeks or less to get the money that you borrowed back as well as any fees that you owe. Don’t borrow with the expectation of taking your time to pay it off sometime in the future. If you are late, those fees are going to steadily increase and you may find yourself sinking financially.

Look Over the Paperwork

The concept seems simple: you need money. A payday loan company lends you money. You pay the money back. But is not that easy. There are fees for borrowing the money, requirements for when and how the money must be paid back, fees and consequences for paying late. Even if you are planning to pay the money back right away and you think you know how much the transaction is going to cost you, read the fine print and ask questions if there is something you don’t understand.

Shop Around

If you are in a panic for cash, you may just want to head to the closest payday lender and get some cash. Before you walk out the door or enter your information online, take some time to look at all of the companies available to lend money. Some may have lower fees and more flexible payment plans. Every company is different and you want to be sure that you are paying the least amount of money possible to borrow from a payday lender.

{ 2 comments }
The Reality of Self-Employment

by Magical Penny on April 18, 2012

LIMITED TIME…FOR 3 days from TODAY, Monday 30th April, there’s an awesome deal going on on products that honestly have helped me, and can help you, make money with a small start-up for $100. Real deal, but only for 3 days.


Back in March I announced on Magical Penny I was striking out on my own.

Strangely enough,  I had not intended to become an entrepreneur.

Growing up I didn’t aspire to work for myself, and didn’t have any entrepreneurial role-models. But over the last two years, I began to realise that I had become an entrepreneur.

It’s what happens when you start working on projects you’re excited about and clients start paying you (fun, right?)

In some ways it feels surreal, but it also feels completely natural. After spending my life on a predictable path (School –> University –> Career), transitioning to self-employment feels incredibly freeing!

If you are thinking of transitioning to self-employment, here are some things I’ve found invaluable over the last few weeks:


Blessing my Opportunity Fund

If you are thinking about the self-employment path, you should definitely consider building up your  ‘Opportunity fund’ (and you should do it even if you don’t have entrepreneurial ambitions)

As I sit in my empty home, staring at an empty page, it’s comforting to know I’ve got savings to keep the lights on and food in my stomach as I work out my next move. I would hate to be worrying about money when I’m trying to be creative and open to new possibilities and adventures.

Knowing I can survive for several months, regardless of how things work out in this new life is a good feeling. So start saving those pennies.

Work on projects on the side

Truth be told, despite the awesomeness that is an opportunity fund,  I haven’t needed to dip too much into the fund because I’ve actually been making revenue since I became self-employed.

In fact, I made more than a day’s salary on my FIRST DAY of being self employed – very much a wonderful surprise!

But it wasn’t luck.

I already had platforms and projects I was involved with before I became self-employed, which has helped a lot.

To be candid, this site, Magical Penny has been one good source of revenue for me since I began working for myself. You may have noticed a few more adverts on here, for example.  I’m not counting on living on advertising revenue alone but having a source of income from day 1 is better than not.


Build an Amazing Network


Meeting incredibly accomplished, driven, talented, giving, new friends

My ‘opportunity fund’ was a real catalyst for change because it funded an amazing trip to South by South West.

Booking a fight was the first thing I did after my last day of traditional employment – allowing me to network and party with some of the top creative minds on the planet, in Austin, Texas.

Over the next week, I had the most amazing time and met some incredible people doing important, amazing, inspiring, impossible things.


The internet allows you to discover, collaborate and work with amazing people who you might not have had access to in the past. But meeting these same people in person allows you to build deeper relationships and simply have fun with people who understand the self-employed (internet) lifestyle.

We’re all in this crazy world together and the power of a solid network of talented individuals cannot be overstated.

Already the relationships I formed or strengthened have begun to pay off in my life and my fledgling business.

These people also inspire me as I sit at my desk with a blank page, about to begin writing the next chapter of my new life.


Remember you don’t have all the answers
If any of this has resonated with you, you might be inspired to become self employed yourself. Whilst I won’t cheerlead you into that decision (I’m far too early on this journey myself but if you want to be persuaded you could read this… ), I will say that it’s only natural to be a little apprehensive about not knowing all the answers.

I certainly don’t have everything figured out. But don’t let that worry stop you if transitioning to self-employment is a meaningful goal for you.


Regardless of your current situation, you can find a way to build an opportunity fund, work on meaningful projects, and develop your network by reaching out to people doing cool things.

Once you’re doing that, then all you have to do is start hustling and working to help other people.

Help enough people and you won’t need to worry about growing your very own magical pennies 🙂

That’s my plan, anyway.


What do you think?

Let me help you learn to save and start investing and I’ll send occasional emails to you to help you on your way.

{ 9 comments }

Are you extending your home? Make sure you consider the implications for your home insurance policy

Whether you’re extending your home, or simply redecorating, it’s always good to make sure your home insurance policy is up to date.

Building an extension is a great way to gain extra space without the hassle of moving. But you need to be aware that some extensions might have an impact on your home insurance policy – so do check before you start work. And it’s important to keep your insurer informed while you’re doing the work too.

With the high costs of buying a house, it’s no surprise that more and more people choose to stay put and expand their existing home instead. They may convert their loft to give them an extra bedroom and bathroom, or add an extension to make more space for an addition to the family. Adding conservatories is also very popular as they can create a very light and open space.

Other extension plans may involve changing how the living space is used. For example, if you want to be able to work from home, you may decide to convert your garage into an office, or build a summerhouse at the bottom of your garden so that you’ve got a designated work space away from your living area.

 Whatever your expansion plans, it’s important to check where you stand with your home insurance. And if your existing insurance is getting close to its date of renewal, you can also get some home insurance quotes to find the best deal.


Make sure you use trusted tradesmen

It’s a good idea to do your homework when you are using tradesmen or craftspeople like builders, plasterers, electricians and carpenters. Choosing the right one can be the difference between a good and bad job. Make sure they are reputable and qualified to do their work.

The best way to do this is to check that they are registered with a recognised governing body. Also, ask around with your family and friends to see if they can recommend somebody you can trust and rely on. And be sure the tradesmen you use have their own insurance for any work they carry out – as most home insurance policies will not cover them or their work.

Whatever you’re doing to your home, you should always keep your insurance company informed and updated. And whether you’re doing work or not, you should always have the right home insurance policy in place.


Halifax offers both home and contents insurance together. Visit Halifax’s website to find a great deal today.

{ 0 comments }

Energy Myths Exposed

by Magical Penny on March 30, 2012

The sunny weather in the UK recently might have made you forget about heating bills for a while, but it’s something you need to always be conscious about as minimising your energy usage and finding the best deal can have a big impact on the amount of money you can save more exciting and meaningful things!

Energy Myths Exposed

Source: Find Energy Savings

How do YOU save energy?

{ 7 comments }

March Carnivals

by Magical Penny on March 21, 2012

It’s Carnival Time!

Personal finance blogs have been such an inspiration for me over the years. They make the topic of finance less taboo and less mysterious.

This can also be inspiring and inspirational. Reading personal finance carnivals allows you to browse a selection of the best blogs and articles, curated by the host of the carnival: more quality articles in one place.

Magical Penny is honoured to have been included in a number of carnivals in recent weeks. Click through and enjoy:

  • Financial Camaraderie Carnival
  • Carnival of Totally Money
  • Personal Finance #352 Carnival
  • Carnival of Personal Finance #352


{ 0 comments }

Sponsored Video: Pension Confusion

by Magical Penny on March 14, 2012

This post is sponsored but the views expressed are those of Magical Penny

When you hear the word ‘pension’ what do you think?

For most people it’s a pretty confusing concept. One of the biggest confusions about pensions is what investments actually go into a pension, and how much does one need to have a retirement that does not mean being being cold and hungry.

Understandably with low understanding comes low levels of trust. I’ve heard countless friends and collegues tell me variations of:

“I don’t trust pensions”

OR

“I haven’t got a clue about my pension

It’s a sad state of affairs because a pension can be a great way to save for retirement – mostly because it allows you to invest money you haven’t paid taxes on and the pension pot grows tax-free year after year. You only pay tax when you start taking out an income (generated by the pension pot when you buy what’s called an annuity).

The confusion and mistrust around pensions have not gone unnoticed:


As the video shows, there’s lots a ‘buzz words’ around pensions.

Ultimately though, there are really two types of pension – defined benefit and defined contributions.  The difference is a defined benefit pension promises you a certain amount of money when you retire, whereas a defined contribution pension gives you you a certain amount of money today to use when you retire.

Defined benefit pensions are also known as final salary pensions and have become increasingly less popular as the risk to deliver an income is placed on the employer rather than the employee. This ‘risk’ has been problamatic for companies in recent years as the economic uncertainty have led some schemes into trouble  running out of money in the fund to pay existing pensions.

A more empowered way to save in a pension is through a defined contribution pension:

How a defined contribution pension works

Most private companies these days offer a defined contribution pension and it’s something you should be doing, especially if they offer what’s called a ‘match’ –where the company ‘matches’ what you put into the scheme up to a certain percentage of 3%.

Let’s give an example:

Say that you earn £20,000 a year and your company offers a 3% ‘match’.

This means that whatever you put into the pension account, the company will put in the same up to 3% of your salary. Therefore to get the most money from your company you need to put in at least what the maximum match is. In this example its 3% of £20,000  = 20k*0.03 = £600.

Put £600 of your own money into the scheme and you’ve just given yourself a £600 raise and you now have £1200 in the scheme! Result! You can actually put in as much as you want, up to 100% of your salary but your company won’t put in any more money into your account than the ‘match’ amount.

As you can see it’s worthwhile but its not the whole story –you need to consider how this money is going to grow and keep up with inflation. You do this by having your pension contributions invested automatically in various investment funds.

Even if you don’t have an employer match it’s worth looking into if a personal pension of your own is good for you.


Ultimately, pensions have a bit of a bad reputation given the ever changing rules about them and the failure of some pension schemes to be transparent in what you can expect to receive when it comes to retire. However, with a defined contribution pension you can receive free money today to help fund your future and be in more control than ever.


{ 3 comments }

I’m not an expert in US Tax Law, but thankfully my blogging partner at TOTO, Connor is. If you file in the US, for more information about how you can rock your taxes be sure to visit Tax On Tax Off

It’s Tax Season in the US!

Form 1040, which is the most comprehensive income tax return that can be used for 2011, has a number of changes from the prior year.

The 5 key changes you need to know for filing your 2011 income taxes

Schedule D is revised

Rather than listing capital gain and loss transactions on Schedule D, with additional entries on Schedule D-1, there is a new form-Form 8949-for listing short-term and long-term capital gain and loss transactions. The totals are then transferred to Schedule D, which now acts as merely a summary.

New Form 8938

U.S. citizens and residents with certain foreign assets must now complete this new form, attached to Form 1040. Filling this in may be required in addition to the annual reporting of foreign accounts on TD 90-22.1 (which is filed with the Treasury each June).

Self-employment tax is reduced

Due to the payroll tax cut, self-employed individuals have a 2-percentage-point reduction in the employee portion of Social Security taxes. This reduction is reflected in Schedule SE of Form 1040. However, self-employed individuals continue to deduct the full employer portion of self-employment tax as an adjustment to gross income on page 1 of Form 1040.

Increased AMT exemption on Form 6251

The alternative minimum tax (AMT) exemption amount has increased in 2011 to $48,450 for single filers, $74,450 for married filing jointly or a qualifying widow(er), and $37,225 for married filing separately.

Schedules L and M is no longer used

Schedules you may have used last year are no longer needed on the Form 1040 for 2011. Schedule L, which was used for additional standard deduction amounts, and Schedule M, for the making work pay credit, are now obsolete because the tax breaks they applied to have expired.


Have additional questions about your US taxes? Visit Tax On Tax Off today

{ 0 comments }

Big news below towards the end of this article -keep reading to find out!

It’s early March, spring is in the air, and everything seems to be going great.

Well, apart from having a nice girl by my side, but let’s not go there!

Hopefully you have experienced good times in your life too. It’s great when everything is just ticking over nicely.

Until it isn’t.

Life can change, for better or worse, in a heart-beat, and it always helps to be prepared.

This isn’t new advice, of course.

Spend enough time on the ‘net, and you’ll overdose on the number of times you’ll hear:

“Have an emergency fund”

An emergency fund, funnily enough, is money you have set aside in case of an emergency.

Are you putting money away?


It makes a lot of sense but do you actually have one?

For many, building an emergency fund is something that’s on the To-Do list but the act of actually putting money away and LEAVING IT, is a real skill.

It can be very easy to let life get in the way. Perhaps you have begun putting money away for one reason but you find yourself needing to spend it on something more immediate like a car repair or a new boiler for your house.

Even if you are saving for something more specific rather than a general emergency, like a dream holiday to Paradise Falls in South America for example, it can be a real challenge to stop yourself from dipping into your savings.

Are you always dipping into your savings?


Tricks To Stop You From Dipping Into Your Savings

Whilst a strong mindset is the most important thing, here are some things that helped me grow my  Emergency Fund.

1) Don’t call it an ‘Emergency fund’

I don’t really like the negative emotion attached to the name. For me I respond much better to positivity than negativity so I named my ‘Emergency Fund’ an ‘Opportunity Fund’.

Subtle difference, perhaps, but the name made me more excited to contribute to it every month. Every pay-day I would move more money into my Opportunity Fund and it felt great -after all, I was helping grow the size and number of opportunities that were becoming available to me. I enjoyed the feeling knowing that if my income disappeared I could jump on a plane and pursue new adventures. If things went wrong, I knew that money would not have to be the driving factor in how I would respond.

2) Make it non-negotiable

I used to move money into my savings account and then take it out again if needed something, figuring at least I was gaining interest on the money before I took it out again. However, this is a slippery slope to losing your savings. I only really started gaining traction when I made a commitment to myself that savings were savings for a reason and they should stay locked away.

If you need to discipline yourself further, consider locking your money away in a 1 year bond or certificate of deposit so you are protected from yourself. But make sure that you can access the money in an emergency if you really need it (most restricted access deposit accounts let you access the money if you need it albeit for a fee or forfeiting any interest you may have earned). Paying a fee might not sound that smart but if it protects your money from your self-sabotaging mind, then it can definitely be worth it.

3) Invest More

Whilst you shouldn’t be investing the money in your ‘Emergency fund’, I definitely found myself saving more (and not touching it), once I began investing parts of my savings into the markets. The act of investing made me really appreciate that the money was now earning and growing on my behalf and the reward of seeing it grow in value over time was fulfilling enough to prevent me from wanting to ‘cash out’ and spend my savings. There was also the risk that I could lose money by selling at a bad time, so by increasing my investments, it made me want to increase my emergency fund further to make sure I would never be forced to sell my investments if I needed extra money in the future.

Click for more information about investing.

4) Care

I wish I could say I had a more ‘sexy’ tip  but there really isn’t anything more important:

To CARE.

To care enough about yourself.

To care enough about achieving your goals and ambitions and not letting money issues hold you back.

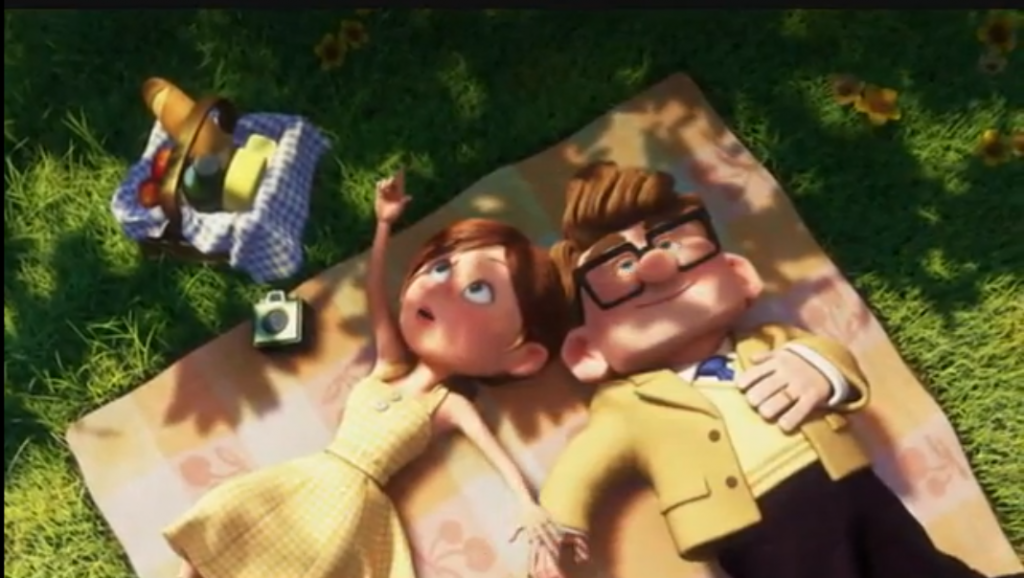
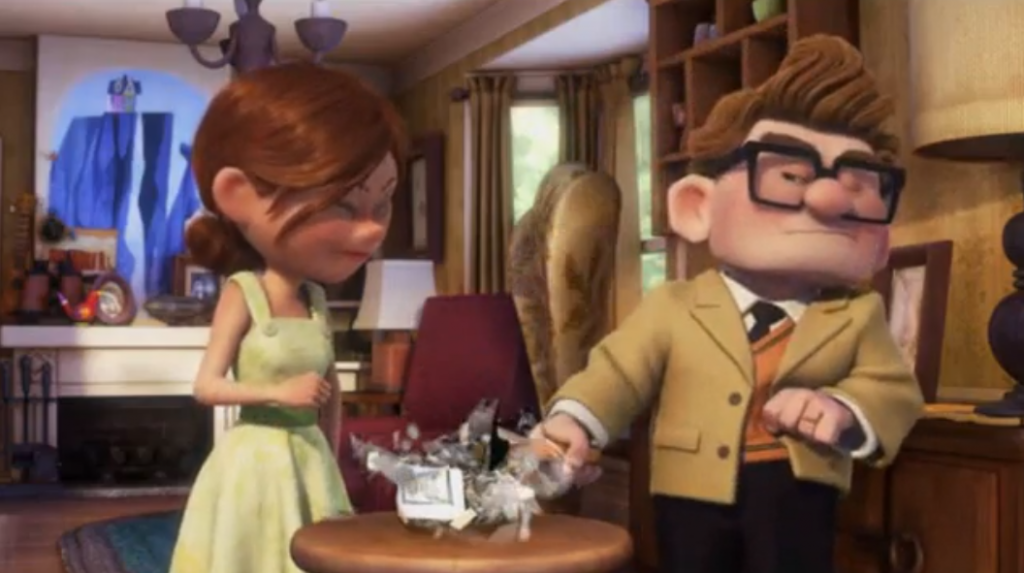
When you think about it, it’s really easy to CARE about making things happen in your life because the alternative, living with regrets about things that never happened, is enough to make any one cry….well, at least I do whenever I watch the introduction to Up:

 Carl and Ellie never made it to Paradise Falls together, because they let life get in the way. Sure, they cared enough to save for the trip, but didn’t truly make it a priority.

Don’t be like them….make sure you are funding your Emergency and Opportunity Funds today.

************************************************************************************

What Do I Know?

This post is inspired by recent events in my life…just last week I ended my employment at my day job and am striking it out on my own!

And having my ‘Opportunity fund’ is making me smile so wide my friends and family think I’m a bit crazy!

I’m feeling the empowerment that building an Emergency/Opportunity fund for yourself can bring.  And it’s awesome that you’re reading this and following along for the ride.

The first thing I did was book a plane ticket to Austin, Texas for South by South West this weekend – to network and party with some of the top creative minds on the planet.

Thank you for being here with me -I want you to succeed in growing your pennies and I want to help you live an empowered life!

Now I’ve got more time than ever to help you do just that!

What are your Emergency and Opportunity Funds for?

Leave a comment and share with the Magical Penny community


{ 15 comments }

Changed Your Mind? How To Avoid Buyer’s Remorse

by Magical Penny on February 29, 2012

A guest post by a reader, Louise.

Picture the scene: you’re browsing on Amazon and you suddenly notice a cool looking camera on sale, 50% off.
It’s a great deal; the camera is a good brand, got good specifications and a lot of good reviews…it’s too good an opportunity to miss! So you click ‘Add to Basket’ and eagerly await the delivery of your shiny new camera.

When it arrives, you take a few pictures of your fireplace, the dog and a few passing cars…then leave the camera in a drawer, occasionally taking it out for an annual trip to the zoo or a family Christmas, but mostly you use the 5 megapixel camera on your phone because, well, that’s good enough and it’s more convenient than carrying around a bulky camera all the time.

If this scenario sounds familiar, you’ve suffered from buyer’s remorse. It can be applied to anything; a gorgeous pair of shoes with unfeasibly high heels; “they’ll be fine if I wear jelly insoles”, a camping holiday down in Cornwall; “if it rains we’ll just go to the nearest café”, or a ‘doer-upper’ house “I can finally renovate my own home!”.

Why Do We Do It?

It turns out that we’re very good at lying to ourselves, especially when we want something. The best barrister in the world couldn’t compete with your reasoning if you really, really want that new £45 Xbox 360 game. We’ll convince ourselves that this item will change our lives, that we’ll get hours of fun or use out of it, and that if we ever do decide to sell it on, we’ll get back what we paid for it.

Sadly the reality is often the opposite. That expensive game will be played for an hour, maybe two, then left on the shelf because your busy life just won’t allow you time to relax and play. The pair of shoes will be worn for one night after which you’ll deem them far too painful to ever go near your feet again, and they’ll sit in the bottom of the wardrobe forever.

As for selling them on; have you ever tried to sell a used game months after it was released? They lose value faster than British cars, and you’d be lucky if you got half of your money back. As for shoes; as soon as they’ve been worn once they’re only fit for a car boot where you’d get offered a pound for them from an old lady who thinks her granddaughter might like them.

Shoes and Savings

Buyer’s remorse isn’t just limited to tangible purchases. Have you ever taken out an insurance policy only to find a better deal a month or two later? Or maybe you’ve gotten a new credit card and later found that the APR is much higher than you expected?

While it’s not buyer’s remorse as such, it’s still a horrible feeling of something being wasted, the object of which will (technically) be much harder to get rid of than a camera or pair of shoes. Opening and then cancelling a credit card could look bad on your credit file, and if you try to cancel an insurance policy you’ll probably face penalty charges.

Avoiding Buyer’s Remorse

Fortunately, it’s quite easy to train your mind to prevent buyer’s remorse from happening. It’s simply a matter of really thinking about your purchase and how it will fit into your life. All too often we think abstractly about something instead of taking the time to consider the finer practical details.

The next time you think about buying something; really think about buying it. If it’s a camera, ask yourself how often you’re really likely to use it. Would you be happy carrying it around everywhere or will your phone camera suffice? If you’re eyeing up a pair of shoes; do you actually have any outfits that they’d go with, and do you already have going-out shoes which don’t cripple you?

In the case of financial products, the key word is compare. Whether it’s credit cards, current accounts, insurance policies or a broadband provider; compare as many different ones as you can. It’s the only way to find out what’s truly the best deal and reduce the risk of buyer’s remorse later on.

Have you ever experienced Buyers remorse?

{ 0 comments }

Introduction to a Stocks and Shares ISA

by Magical Penny on February 1, 2012

We would all love to make a fortune, but most of us don’t know how we will become millionaires. However, it is still possible to make small investments and get a good return on your money (if you’re lucky/make your own luck!), effectively turning a tiny amount into a relative fortune – as long as you invest consistantly and are willing to take on the risk that comes with any investment.

Don’t confuse risk with ‘gambling’ though. It’s a bit different to playing slots for iphone. Both can be fun but when it comes to investing you need to thing about it in a different way.

A great way to invest is in a stocks and shares ISA.

For this type of investment you put your money into an ISA account which then is invested in various stocks and shares (this varies depending on the specific ISA that you have chosen and the options available).

The great thing about ISAs is that your money can grow tax-free, so you don’t have to worry about paying any tax on the interest, capital gains or share dividends you may earn as a result – which is one way you can help turn your small investment into a relative fortune, as the lack of tax helps to boost your return.

You can also choose whether you want to reinvest your dividends in more shares (recommended for simplicity and to compound your returns), and you can generally put as much or as little into your share ISA as you like each month; just don’t go over the total annual limit that is placed on all ISAs which is currently over £10k per year.

Of course, it is important to note the risk that comes with a Stocks and Shares ISA – the stock market is not guaranteed to rise continuously and so your investment has the potential to dip – but if you are able to leave your money in the ISA over the long term, there is a good chance that the investment will grow.

By how much it grows often depends on how the investments inside the ISA perform.

It’s a good idea to investigate the best stocks and shares ISA for your needs, and understand what you are investing in as investment risk varies enormously. For instance, investing in a climate change mutual fund inside your ISA (that invests in energy-conscious businesses) is one of the riskier investments, but it has may perform very well over the long term.

If you are looking to spread out your options, one particular favourite investment is the FTSE all-share tracker fund so you never miss out when the stock market grows. Adding bonds and gilts into your ISA could also be worth considering; these can offer lower returns but they have less risk attached.

Overall, making a fortune requires dedication and care to make sure you make the best investments for your needs and that you manage the risk attached to investments wherever possible. With one eye on the long game and one eye on your current investment portfolio, you should have a decent chance of growing your ISA investment in the months and years to come.


Overwhelmed by your options but want to start investing? Sign up for updates and I’ll walk you through it.


You may also find helpful:

Why A Pension (and an ISA) Is Like A Water-Proof Envelope


{ 2 comments }