Unexpected Ways to Kick Your Finances Back Into Shape

by Magical Penny on April 5, 2017

flexibility in savingsThere are so many great ways to kick your finances into shape when you’ve let them collapse. Regaining control is not easy, but you don’t need to follow the same dull tips and rules that lots of people talk about and point you towards. Sometimes, thinking outside the box and taking a few simple steps can be enough to improve your financial situation. Here are some ideas that you should try out.

Start Being Harsh with Yourself

Being harsh with yourself might sound like something that wouldn’t be particularly useful when you are trying to improve your situation. But sometimes, being firm is the best way to be. If you’re the kind of person who is ill-disciplined when it comes to money matters, a firmer hand a stricter sense of self-regulation could be exactly what you need. So, rather than letting yourself get away with financial mistakes, make sure there are consequences when you take a step in the wrong direction. That way, you won’t be so willing to let them happen again in the future.

Focus on Your Habits and the Mistakes You Most Commonly Make

When you’re in a poor financial situation, there is usually a pretty obvious reason for that. It might be because you make the same mistakes over and over again. When you do this, it makes it very hard for you to turn your situation around and make positive steps in the right direction. That’s because every time you do something good, you will make the same mistakes that you always make and take a couple of steps back. You should focus on these habits and mistakes and find ways to change them permanently this time. That’s the only way to achieve lasting change.


Organise (and Automate) Your Regular Outgoings

We all have certain things that we have to spend money on every month. Yet, these expenses and costs can still come as a shock and surprise when the time actually comes to cough up the cash. If you need help with smart decisions about paying rent or getting the bills paid on time, there are plenty of resources out there. But it should all start with greater levels of organisation. When your regular outgoings are organised, and, wherever possible, automated, your life will be so much easier. You will know how much of your income is going towards these things and how much will be left over.


Grow Your Income in Ways You’ve Never Tried Before

Growing your income, and maybe diversifying it a little, is a really good idea and it can help you get your finances back in shape much quicker. There are always new and interesting ways to earn more money if you’re willing to work more hours. Sit down and think about what skills, abilities and talents you have. We all have them, and many of those skills and talents can be monetised in some way. The extra money you earn from these activities will help get you back in shape, and your income will be diversified in case you never need to shift career in the future.


{ 0 comments }
Adverse Situations Aren’t Permanent

by Magical Penny on April 5, 2017

In life it’s easy to find yourself in an adverse situation. It’s easy to get into a place in life where you are seemingly tarnished with an unfavourable image that is preventing your success or development. However, as easy as it is to find yourself in that kind of situation, it is as just as easy to get out of it. Adverse situations in life are never permanent and can be rectified — you just need to have the courage to fight them.

british pound notesBad Credit Isn’t The End of the World

First and foremost, poor credit is only an obstacle and is not something that need scar you for life. Yes, having bad credit is not good, but it’s not earth-shatteringly bad either. Even if you have missed a few outgoing payments or even been declared bankrupt you can improve bad credit in a number of ways, some of which include: closing any credit cards that you don’t use, seeking sustainable borrowing with a guarantor loan and by, importantly, ensuring that you check your credit report often to ensure that everything is as it should be. And when it comes to poor credit, there are even companies out there that offer services that help those who face it, such as 1st UK Mortgages, who can provide you with support and information on how to remortgage with bad credit. First and foremost, they help those who find themselves facing the plight that is bad credit and help match them to lenders that are willing to work with them, despite how adverse their situation may seem to be.

Sort Your Growing Debts

But adverse financial situations aren’t pigeonholed only to the plight of bad credit, it can also be a term used to describe those who have fallen behind in regards their outgoing payments. Debts, whether they are induced by the stacking up of everyday outgoings and bills, the paying back of bank overdrafts, payments owed for loans or credit cards or all of them combined, can place you in an adverse situation in regards to your finances. However, as is the theme here, you can fight them. The tactic that should implemented above all when it comes to tackling these types of situations is to just ask for help. Now, this may seem like simple advice, but a lot of the time it is not as simple as it seems or sounds. Generally, pride is a huge factor when it comes to not wanting to ask for a loan off of a loved one; however, when it comes to financial adversity, this may be the best option. Before you even attempt to seek help from external sources, companies or services you should ask your loved ones, whether it be your mom, dad, other-half, sister, brother, best-friend, colleague, cousin or even your child — you should never allow pride or ego to stand in the way of you asking for financial assistance when you really need it. When pride is thrown to the side, only then can start your ascent to escaping the adverse situation you landed yourself in. If you are particularly scared of taking such a venture, then here are five tips for when it comes to asking financial help.

life insuranceGet Organised

However, sometimes financial adversity runs far deeper and cannot be overcome by merely borrowing money. Debt problems have the power to place anybody in an adverse situation that is so bad it seems that there is no escaping it; however, there is always a lifeline, and more often than not that comes in the form of debt consolidation. When a plethora of debt is mounted with a host of different providers, i.e. when different companies and institutions demand bills, loans, payments and overdrafts, at the same time, debt consolidation can help ease the stress by throwing them all into one basket, thus ridding you of the problem of having all of those horrid outgoing payments all at different times of the month. So, if you find yourself in an adverse situation in regards to the amount of money you are owning, make sure to take up the services that are offered by professionals in the field.

It is estimated that one in six adults in the UK have financial worries, which is why it is imperative that, even if you find yourself in an adverse situation, you remember that you’re not alone in the plight. There are always ways out, if you are strong enough to find them — only then will you be able to face your situation. And once they are faced you can take pride in the way that you have overcome your demons and revel in the fact that you have not been left permanently scarred by the adverse situation you were once in. For tips on how to deal with adverse situations in general make sure to click here.

{ 0 comments }

Fun Cash-making Side Gigs

by Magical Penny on April 5, 2017

Everyone would like a bit of extra cash to spend or save. You don’t necessarily want to become a millionaire. You’d just like some more money to spend on going out. If you want to up your disposable income a little, a flexible side gig is ideal. And if you can have fun when you’re doing it, then it’s even better.

Making Things to Sell

If you’re in any way crafty or creative, selling things you make can be a great way to make money. In fact, it becomes a necessity for some enthusiasts, once they’ve filled their home and given gifts to everyone they can think of.

Play Games

Playing games online can be a way to start making money. Of course, there are those that are based on chance. But there are also more skills-based games, such as e-sports tournaments, which can be a great way to win some prizes.

Make Money from Your Bike

Do you enjoy cycling around? If you’re going to be cycling anyway, you might as well make money. You can add advertising to your bike, start leading cycling tours or outdoor fitness classes, help people repair their bikes, and more.

Betting

Betting usually involves a level of risk, but it can pay out if you know what you’re doing. In addition, you can try matched betting to avoid having to risk any capital. Using free bets from brokers allows you to make sure you won’t lose any money. But it’s important you understand the basics of betting first.


Credit to Casino Pros

{ 0 comments }

Increasing Your Income: Tips and Idea

by Magical Penny on April 5, 2017

Just about anybody can increase their income, however much they earn right now. You might think there’s no way for you to make more money, when in fact, changing that mindset you have is key to ensuring more money than ever comes rolling in. Here are some tips and ideas that could help you!

investingAsk For A Promotion

Why not ask work for a promotion? If you don’t want a promotion, it’s totally possible to ask for more pay too. However, don’t just go up to your boss and ask for something like this without a solid argument as to why you should get it. If you’ve been sitting on your thumbs for a while and not really contributing at all, they’re going to have a hard time justifying why you should get a pay rise. If you really want this pay rise, put something convincing together and see what happens. If you don’t get one now, your boss may be able to give you some pointers on how to get one.

Figure Out The Best Things To Invest In

Investing your money in a wide variety of things can help you to build up your finances in the long run. You need to be prepared to be in it for a long time, as the investments you make won’t pay off right away. In fact, some of them may cost you quite a bit in the long run. Look at Bridgebury Real Estate and get an idea of whether investing in property is your thing. You can also invest in things like stocks, gold, and more!

Find Out Where You Could Be Saving

Take a look at your life and finances and figure out where you could be saving. Maybe you visit your local coffee shop every day for lunch and spend some money there. If you packed a lunch, just house mortgage UKthink of how much money you could save! This doesn’t mean you should struggle and cut back in every area of your life. It just means spending a little smarter and working out what’s more important to you!
Get On Top Of Your Finances

Get on top of your finances and stay on top of them. Know how much you have coming in, and how much you have going out. Start tracking every single thing you spend. This will make it so much easier for you to figure out where you need to cut back.

Find Ways To Make Passive Income

Finding ways to make passive income is a great idea, as it means you get to increase the money you earn as you sleep! There are hundreds of ways to do this, and if you do it right, you could do minimal work for a lot of money. You’ll need to work at it and be patient, but eventually you could make money for doing nothing!

Hopefully you found these tips and ideas really helpful. Do you have any of your own that you like to use for upping your income? Leave them below!

{ 0 comments }

The lifetime cost of owning a car

by Magical Penny on April 3, 2017

One of the biggest line-items in a household budget is likely to be transport-related (You have a monthly budget right?)

Having a car is one of the most convenient modes of transport, but it certainly isn’t the cheapest.

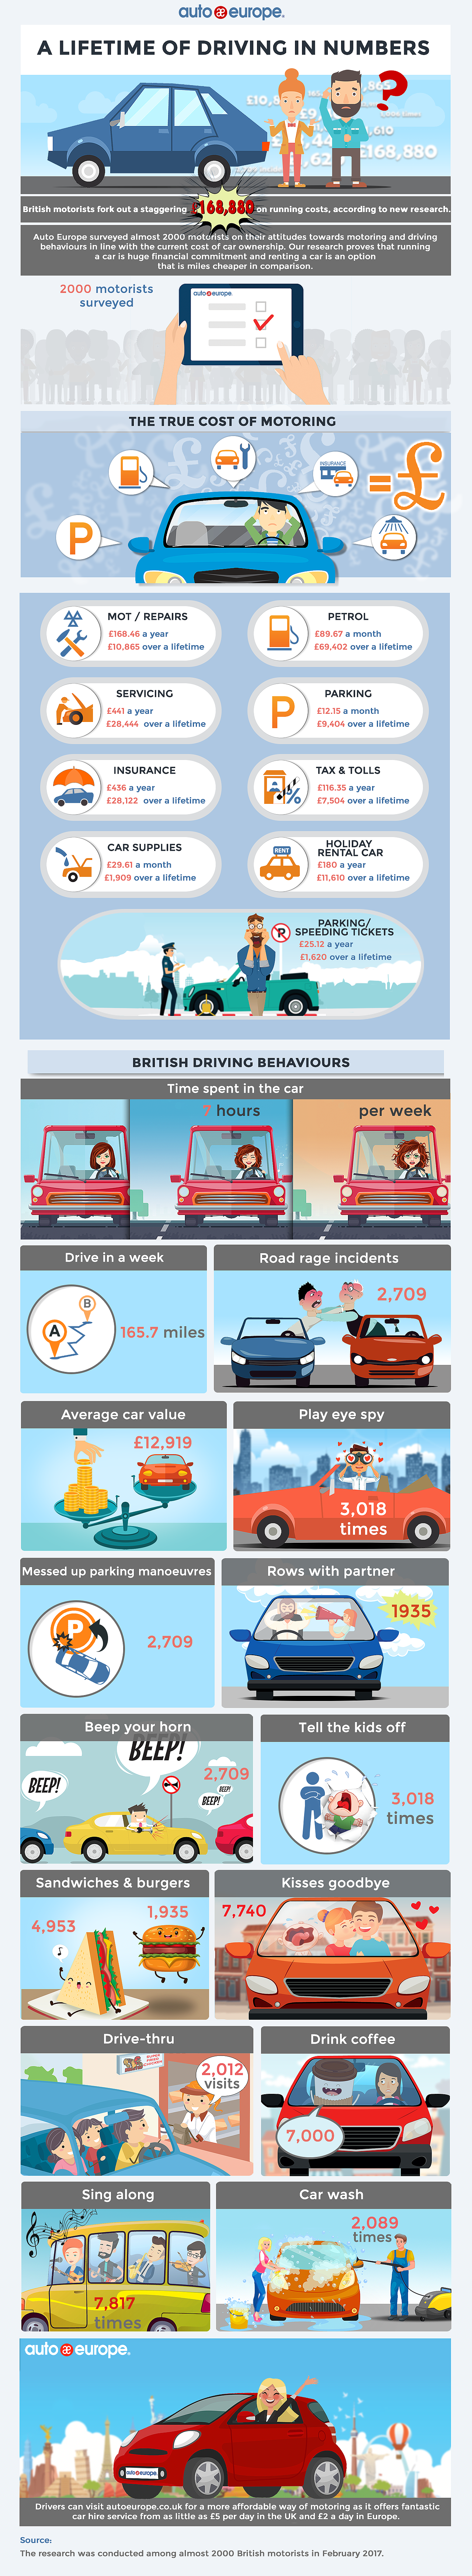
According to new research, the average motorist will spend £168,880 in their lifetime on their car travel alone!

This includes spending nearly seventy thousand pounds on fuel over the course of a lifetime, and forty thousand on MOTs, servicing and repairs.

The research was commissioned by car hire company autoeurope.co.uk  and found on average, travel 166 miles on average in a week, which when multiplied over a lifetime is  the equivalent of 22 loops around the earth.

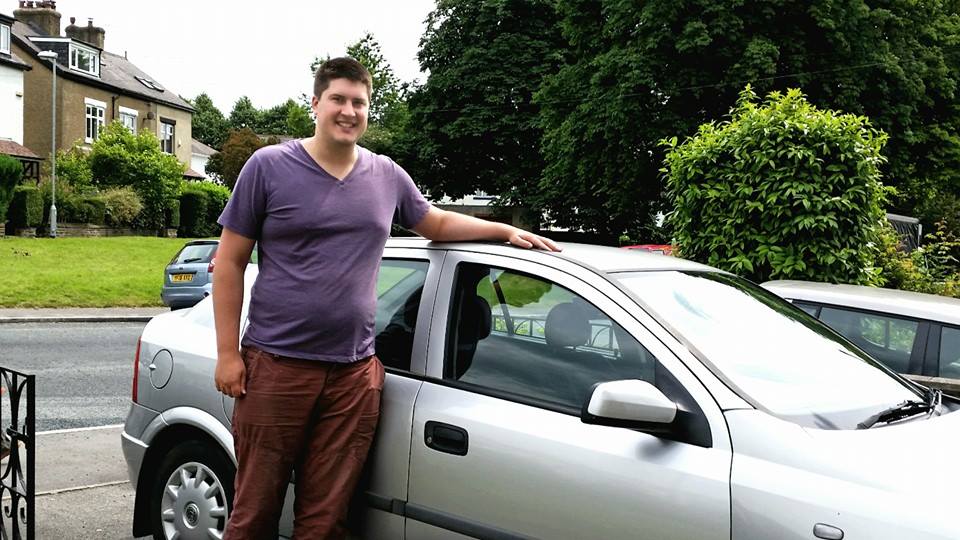
My first ever car

I didn’t own a car until my late 20s and now having enjoyed the use of a car for over 3 years I can see first-hand that running a car and its associated expenses is a large financial commitment.

The numbers get even bigger if you’re tempted to buy brand new cars and replace them often. The research found found the typical Brit has a car worth £12,919 and every family owns 1.6 vehicles as an average.

How does your car(s) compare?

Amazingly, the study also found we sing along to the radio 7,817 times in our driving lifetime. I think I’ve already hit that number already so I might need to keep it down in future!

Ultimately having a car is great, whether you buy and own it outright or decide to opt for affordable car hire but whatever you do, make sure it’s an informed decision and you’ve run the numbers to calculate how much you are really paying to have your own set of wheels.

AE_Cost-of-Motoring(PNG)


{ 0 comments }

The Habits Of A Financially Healthy Person

by Magical Penny on April 3, 2017

couples need to work together with moneyDo you ever look at someone who seems to simply have everything to do with money in order without nary a hiccup and feel that surge of envy? Well, put that behind you. There’s no real difference between people who are good with money and those who aren’t. Financially healthy individuals with good habits weren’t born with them. They learned them. Many of them through trial-and-error. We’re going to skip the error bit and look at the habits you should be learning right now.
 

They see where they’re at

A lot of people would save themselves a lot of headaches if they simply took the time to check their finances every so often. Every day, you should set aside a money minute to look at your bank balances, transactions, and any progress towards savings goals. It gives you an idea of where you’re at and where you’re going. It also incentivises you to keep moving, rather than ignoring it for too long. Check your bank statements every month, too. Identify any purchases you could have skipped or services and subscriptions you didn’t use. It’s a lot easier to keep more of your money when you start thinking about what expenses could be painlessly culled.

They have aims

An important part of the last point is the mention of aims. If you don’t have them, it’s always going to be harder to keep money aside. When we have an objective, our efforts are simply more focused. A good long term goal for anyone is financial freedom. To be free from debt and the threat of it, to not be beholden to chance and creditors. What are the steps you can take toward financial freedom? Clearing any debt is an obvious one and should be the first step. But then there are goals to protect that freedom, too. Setting up an emergency fund so you’re not dragged back into debt, for instance. Diversifying your income so you’re not entirely reliant on a job without a financial future. Don’t make personal gratification your outcome. Delay it and let it be one of the pleasant side effects of meeting your real goals.

investingThey invest and save

As you can see at http://www.bankrate.com/, there tends to be a lot of debate over whether you should invest or save. At some point, however, you’re going to realize the answer lies in a bit of both. This is part of the income diversification that you’re going to use to protect your financial freedom. It’s not enough to find a good savings account and a good investment and just let it lie, either. You need to keep working on it. Look for the best options, reap your gains and reinvest. Keep building different channels of bringing income in. It takes a bit of work keeping so many irons in so many fires, but it’s effective.

They learn to control their impulses

As we stated above, you need to learn how to delay gratification. Not just in terms of changing goals from ‘I want a new TV’ to ‘I want to have invested a thousand dollars this quarter’. You also have to be mindful of the habits that are keeping you away from financial health. Especially when it comes to impulse buying. There are a couple of habits that can help you cut a lot of the fluff out of your expenses. First, if you have to borrow to buy it, you can’t afford it. Then, give yourself fifteen minutes on any potential impulse buy to reconsider. If it’s bigger, make it a day and sleep on it. Remove immediate buying from your mind entirely.


If they NEED debt they work on their credit

ImportantBorrowing money costs money, and should generally be avoided. However if you need to borrow money on bigger essential purchases, having good credit can save you money. Advice from places like https://creditrepaircompanies.com can be useful for those who need to borrow money for any reason. A good credit score can get a better deal on a home, on business loans, and when buying a car on credit – the latter is an expensive way to operate a vehicle but if you really need a car then getting the lending for it as cheap as possible is a good thing.
They simplify what they can

The whole of your personal finances isn’t simple. But there are a lot of tasks that can be made a lot simpler. For instance, you could consider automating your savings. You can set aside the portion of your budget dedicated to your financial goals and have it transferred from your account every time you get paid so you never spend it accidentally, leaving yourself nothing to save for this period. You can automate bill payments, too, but a lot of people don’t like doing that. Instead, many will recommend you set all your bill payments on the same day, if you’re paid monthly, or on two days throughout the month, if you’re paid more regularly. Forgetting to pay bills is a habit many share but one that’s really quite easy to get rid of.


personal finance readingThey read

Finance can get a lot more complicated than what we’ve gone through above. For instance, you might want to figure out how to really budget. Or how to weigh an investment portfolio. Or even habits of thinking that will get you even more financially savvy. There’s more to finance than any one post can cover. That’s why people who really care about their money read. They go to sites like http://www.businessinsider.com/ and give themselves a book a year to read. Your finances are like a body. They don’t get healthy all at once. You have to put the time and the effort in and learn how it all works.

The habits above are going to make you more mindful of your finance, a better decision maker and financially a lot healthier in general. But the most important tip comes last. Don’t delay. Don’t procrastinate. Every second you waste decreases the positive benefits of learning the habits above.


{ 0 comments }

A Step by Step Guide to the Road to Financial Freedom

by Magical Penny on April 3, 2017

autumn statementFinancial freedom can sometimes feel like an oasis in the middle of the desert. There it is shimmering away somewhere in the distance, but the minute you start to get close, it disappears. If you don’t have the right strategy in place, you could end up striving away for years and years only to find that you have got no closer to your goal. Though there is no single route to financial freedom, there are a few steps that you can take so you start moving in the right direction.
 

Create A Plan that Will Get You Where You Want to Go

Like most things in life, good things start with a good plan. Financial freedom is the long term goal, but you will need to set yourself a series of subgoals to actually get there in the first place. Think about ways in which you will increase your income over time, whether by switching jobs, getting involved in the stock market or making a sound commercial investment. Think about how you will control your spending habits, as well as paying off any outstanding debt. Work out how to up your savings and define your long term financial goals.

The Art of Delayed Gratification

In an instant gratification culture, the art of delaying this is one of the best financial tricks that you can teach yourself. Realise that the sacrifices you are making now will benefit you in the long run. Again, make a plan that details all your expenditures and work out the things that you can cut back on. Accept that the sacrifices you are making now are for your long term success in achieving financial freedom. If there are people in your life who negatively influence your spending, make a commitment to ensuring that this doesn’t happen in the future.

financial newsKeep Moving Forward


Steadily increasing your income while keeping your spending level the same will pay off literally in the long run. When people receive a pay rise, they often see this as an excuse to spend more money even though it won’t significantly improve their quality of life. Always try to improve your skills over time so you are more valuable to employers and look out for better opportunities wherever they may exist.

Save Money Regardless of Income

Even just putting a little aside every month can make all the difference in the long run. Many people say to themselves “I’ll start saving money when…” But the problem is that “when” never comes. Even though savings accounts don’t offer a huge amount of interest these days, the more you have, the more likely you will be able to generate some sort of passive income for yourself.

Diversify Your Income

In today’s sharing economy, people can make money in more ways than ever. For example, many people are making extra cash by renting out a spare room, offering storage space and renting out their driveway to name just a few.

{ 0 comments }

houseIn this day and age, most first time buyers are looking at putting down a deposit of between 5 and 10 percent of the asking price. When you’re paying rent and bills every month, it can be difficult to save, especially when the end goal seems so far away. If you’re aiming to become a first-time buyer, you may feel like you’ve arrived at this point in your life at the worst possible time. It’s not an ideal time to be a first-time buyer, but there are ways of getting onto the property ladder, so try not to be disheartened. In many cases, buying is not the only option, and it’s always worth weighing up the pros and cons before you make a decision. Hopefully, this guide will help you make up your mind if you’re not sure which path to take.
The pros and cons of buying

Most of us grow up with dreams of settling down with a partner and holding the keys to our very own castle. Unfortunately, it’s no easy task getting onto the ladder these days, and there’s a lot to think about if you are considering buying. Firstly, there’s a deposit to save, and this is no mean feat. You may need up to £20,000 just to put a deposit down, and this is before you factor in additional costs, such as surveys and first time buyer solicitor prices. Buying may be a convoluted process, but it gives you an asset, which will hopefully appreciate with time. When you’re a homeowner, you have freedom to do what you like with the decor and design, but you also have to assume responsibility for the upkeep of the house. If the boiler goes, for example, you can’t just ring a letting agency and arrange for somebody to call and fix it. You’ll be liable for the cost of repairs.


remortgage house loanThe advantages and disadvantages of renting
Renting is often a convenient option for people who can’t afford to buy at the moment and those who move around frequently. Some people also prefer the freedom renting gives you, as you can take on short-term contracts, and you don’t have to assume responsibility for upkeep costs. The rental market in the UK is booming, and this does mean that prices have increased steadily. When you rent, you may end up paying a lot more each month than you would if you took a mortgage to buy a house. When you rent, you’re also at the mercy of a landlord or landlady, which may mean that you’re restricted when it comes to making the home your own.

If you currently rent and you’re hoping to buy, or you want to move out of your university home or the family home and take the next step, you may be considering your options. There are pros and cons to both renting and buying, and the choice you make will often come down to your financial situation. Even with the introduction of affordable housing schemes, you’ll still need a significant amount of money to get started, and the reality is that many people find it hard to save for a deposit.

{ 0 comments }

The vast majority of people want to be wealthy – and healthy. But many don’t see how the two positions are intrinsically linked. Research suggests that the wealthy are more likely to be healthy, too, and the same goes in reverse – the healthier you are, the more chances you have of becoming healthy, and thImportante more money you can save to make it happen. With this in mind, we thought it would be a good idea to look at some of the ways that improving your health can also help to improve your wealth. Let’s take a closer look at a few things you can try to save money and lengthen your life.


Diet

Fast food and junk food are both often thought of as cheap. But are they really? The simple truth is that cooking your own food from healthy ingredients gives you a lot more control over what you consume, and will also save you a lot of money at the supermarket checkout. Vegetables, fruit and whole grains are all cheap, and you can combine them together to create wonderfully tasty dishes that boost your health and cut your grocery bill. Consider sugary drinks, too – the scourge of many dentists and dietitians. Switching your sodas for plain old tap water will save you a considerable chunk of money over the course of a year, and also keep you hydrated and healthy.

flexibility in savingsExercise

Want to save money and improve your health? Stop driving your car so often. Walking to and from the shops or work means you miss out on the opportunity of a good stomp to get the circulation going. And it also costs you a lot of money at the pumps at your local garage. If walking isn’t your thing, what about riding a bike? You can pick one up for a few hundred pounds, and if you compare bike insurance online, you will see that it doesn’t cost a lot to cover yourself for accidents and theft – far less than it does for your car. It’s also worth considering that once you start to exercise, and break through that critical two-week difficult barrier, you will begin to appreciate your body a lot more. You stop eating so much junk, spend less time sitting down, and try and be as active as possible – all of which saves you from spending money on other things.

Bad habits

It’s not uncommon for your bad habits to cost you a significant amount of money. A pack of twenty cigarettes, for example, can cost you over £9 these days and damages your lungs and heart for the pleasure. Alcohol is also becoming increasingly expensive – £5 pints are not an uncommon sight in the major city centre bars around the country. Imagine how much money you could save and how much healthier you would be if you managed to quit these bad habits? If you were to stop smoking altogether, you would be, in effect, paying yourself £3,285 on a 20-a-day habit every year to improve your health – who wouldn’t want a wage rise that big?

As you can see, becoming healthier can have an enormous impact on your finances – why not give it a try?


{ 0 comments }

Save Money by Avoiding Bad Advice

by Magical Penny on March 28, 2017

investingIn recent years, we’ve become more and more reliant on professionals to teach us everything from how to renovate our homes to how we should save and spend our money. This is generally because we’re more aware of all the rules and regulations surrounding things we used to take for granted, such as building an extension on our house or starting up a website and using a name that is similar to a well-known brand. You might be accidentally treading on copyright infringement, you could be borderline plagiarising work, or you could be committing offences without knowing it.

Unless we want a nasty surprise and a lawsuit on our hands, we need to seek professional advice to navigate the maze that is law. Unfortunately, this means that we have to spend extra money on hiring a professional for the sake of advice. Although it sounds expensive, think of it this way; you’re paying for someone to advise you on a subject that they have spent years learning about and studying. When you think of it that way, it’s invaluable advice that you won’t find anywhere else—or is it?


Only hire someone after due diligence

With the internet, we can find information on anything from raising a baby to mastering money. In addition to informative articles based on factual information, there are also thousands of blogs on the internet that share experiences with us. It could be someone who’s going through a nasty illness, someone who has been sued by a large corporation for silly reasons, or someone who’s just starting up their first business. These journal-like blogs are a dime a dozen but they all have one thing in common; they are genuine experiences with a lot of photographic proof and statistics.

With so much information available on the internet, you can learn a lot about any subject within a short amount of time. Some information, such as professional study courses, are locked behind payments or a subscription. However, even universities such as MIT make their lectures free, giving anyone and everyone access to quality information for the purpose of learning.

ftse100In short, only hire someone if you really need to, like for professional financial advice where tax and investing goals require sophisticated planning and well-researched investment analysis. The last thing you want is to file professional negligence claims because the person you hired knows less than you do after a brief search on the internet. There are plenty of “professionals” who claim to know more than they do but all they’re after is your money. Not only can bad advice and poorly-executed jobs be dangerous, it’s also going to cost you money that they don’t deserve.

Stay away from subtle advertisement

We’ve all been on a blog that lists some of the “best” things to buy. Whether it’s a top 10 list of the best vacuums or a top 5 list of the greatest keyboards ever, you can almost be sure that they are just writing articles for the sake of their affiliate programs. In other words, by clicking those links on products they recommend, you’ll be taken to a site where you can buy the product and they will receive a small commission for the sale. However, the reviews themselves or the advice they give could be completely wrong, and they’ve simply just copied information or made up lies about a product just so that you’ll buy it.

That’s not to say that every piece of information on the internet is wrong. Some people make legitimate top 10 lists of products they actually use. The best way to discern if it’s just a bunch of lies or actual advice is to read the context. If the reviewer or article author doesn’t go into much detail into each product and makes it sound too good to be true, then it’s probably just a big lie designed to make you spend money for their commission.

{ 0 comments }