Save Money by Only Buying the Things You Really Need

by Magical Penny on January 7, 2014

If you want to build a secure financial future for you and your family, you need to start saving money from now.

Many people try and track their monthly expenses by keeping a spreadsheet.

This gives them an accurate record of where their money is being spent and how they can stick to a budget. If you want to track every penny that you are spending, and avoid impulse-buying, then keeping a record of your monthly outgoings would be a good start. Here are some more tips on how to be more frugal.

Eating out can be fun, but it will work out more expensive than cooking your meals at home.

Taking your family to a restaurant once a month rather than once a week would make financial sense, and soon you will realise just how much you can save this way.

Adopting a minimalist wardrobe is another tip to save money.

Take a look at your current wardrobe and decide whether you actually need to buy any more clothes.

Using the library instead of buying books and DVDs will save you even more.

Some libraries allow their members to borrow up to 6 books and DVDs for up to two weeks, so why buy when you can borrow. You can easily find free games to play on the internet instead of buying from your local store. There are also websites that allow you to download free movies so you won’t have to go to the cinema.

By practicing frugality, you will become more aware of how much you are paying for items, and you will know whether you are getting a good deal or not. Collecting coupons and going to car boot sales will certainly help you save money.

Putting money away in a savings account means you won’t be tempted to spend it all.

When you get paid, set aside the amount you need for food, bills, petrol and other essential expenses. What you are left with can be put in a savings account to earn interest. This way, not only your savings will grow, but you will also have something for a rainy day.

Bargain shopping is another great way to save money while buying the items you really need. This tactic will stop you from spending too much on non-essential things. Next time you go shopping, avoid designer boutiques and head straight down to flea markets.

If you don’t have the time or you are not keen on searching all the shops for sales, then opt for the convenience of the internet to buy what you need. The best thing about the Web is that you can browse through websites from the comfort of your own home, whenever you have the time.

You can also order your groceries online to save money.

Using a service like Milk and More will help you prevent making impulse buys as you will only be purchasing what you really need. The best thing about this website is that it has no minimum order and delivery is free of charge. All you have to do is sit back and wait for your groceries to arrive. Before placing an order online, make sure you prepare a shopping list of all the essential items you need so that way you don’t overspend.

{ 0 comments }
4 Unique Tips for Elder Care Planning

by Magical Penny on December 30, 2013

Elder Care PlanningWe all should be aiming to grow our pennies to help us live richer lives.
You may not have thought about it but  making plans for your own care later in life or figuring out how to provide for an elderly parent or other loved one is an important step in this process.

Unfortunately, until you have experienced the unique challenges that can unexpectedly arise in old age it can be very difficult to know what questions to ask and what arrangements to make. To help in that regard, here are four tips from those who have “been there, done that” when it comes to elder care.

1) Include Alzheimer’s Planning

First of all, prepare for the possibility that the senior will suffer from debilitating memory loss and confusion related to Alzheimer’s or dementia. One out of every three seniors will die of Alzheimer’s or other forms of dementia and the presence of that disease can radically complicate elder care. That’s why it is prudent to assume that it may be a real possibility – otherwise your carefully crafted plans could be upended and rendered obsolete by the onset of dementia and all the problems it brings.

People afflicted by this disease become unable to cognitively manage their own affairs. They may experience symptoms including fear and panic-inducing confusion, short term memory loss that impairs their ability to take care of themselves, or outright psychotic breaks from reality. The prevalence of Alzheimer’s disease is growing as the population ages, and it is estimated that within the next 10-12 years, the number of Americans with Alzheimer’s will exceed seven million. That’s a 40% increase from where we are today, so if you are doing prudent planning you must take these statistics into consideration.

2) Get Your Documents Sorted Out

To ensure adequate care, you need an adequate plan and that includes health insurance, retirement savings, life insurance to provide for your family and documents such as a Last Will and a Health Care Power of Attorney. Sadly, less than half of all Americans have an estate plan.

The implementation of a comprehensive plan can be legally and financially complicated, so do yourself a favor and start early. Keep in mind that these days most people have digital assets including things like important email accounts, smart phone accounts, digital scrapbooks, bank accounts, brokerage accounts, and online businesses. Make an inventory of all significant digital or online assets along with passwords, and keep that valuable information in a safe, secure place.

3) Seek Out Geriatric Specialists

One of the things family members caring for seniors frequently learn the hard way is that there is a world of difference between ordinary health care and geriatric care. Many seniors complain that they cannot even get appointments with doctors and dentists because once the receptionist finds out that they are in their 80s the doctor’s calendar mysteriously fills up. After all, it can be more challenging to treat the elderly and they may represent a greater liability for health care providers who aren’t experts at working with older people.

Treating a patient with Alzheimer’s also exponentially complicates the situation. A simple dental checkup or appointment with an eye doctor to get a new pair of glasses can be fraught with drama and difficulty.  The solution is to enlist the help of health care providers in all the various fields and medical specialties who have additional credentials as geriatric specialists. They are trained to work with the elderly and they know how to deal with the complexities while providing that extra dose of comfort, reassurance, and respect.

It’s also important to note that women are generally healthier than men, but they should not interpret that statistic as an excuse to skip this step. In fact, the opposite applies because women usually live significantly longer than men, which increases the need to shop for doctors experienced in geriatrics.

4) Shop for a Continuum of Care

Last, but not least, when doing research into retirement or assisted living facilities, think long term. Many seniors spend extraordinary amounts of time and money to find an appropriate place to live, but they overlook the fact that the majority of retirement homes and similar facilities do not offer a complete continuum of care. The key question you need to always ask is “If I live in that kind of facility and get sick, what happens then?”

There are quite a few facilities that specialize in Alzheimer’s care, for example, but they do not, however, have the resources to care for people who need skilled nurses. Once a person requires help to get out of bed, for instance, whether it’s because of a broken hip or recovery from some kind of surgery, they may no longer be able to live in a facility. That will require starting all over again to find a new place to live that offers skilled nursing services, and nobody wants to deal with the challenge of that kind of project plus the subsequent move – maybe to a completely different town – at a time like that. The solution is to buy into a facility that offers all three levels of living arrangements – independent living, assisted living, and skilled nursing.

Tom Kerr writes for CompareCards.com in addition to others. He has been an avid writer for years, even winning awards for work he’s done.


{ 1 comment }

Find Your Lost Pensions

by Magical Penny on December 23, 2013

It’s surprisingly easy to lose track of your pensions, especially if you’ve changed jobs a few times and moved around a bit.
How I Ended Up With Multiple Pensions

When I started work after university I was offered a company pension scheme, which I diligently took up.

It was a defined contribution pension which means my employer would give a contribution and I would give a contribution and this money would build up my pension ‘pot’.

This is different to a defined benefit pension, otherwise known as a ‘final salary’ pension that uses your salary and years of service to determine how much you are entitled to at retirement.

Whilst final salary pensions are often more generous and puts the risk on the employer rather than the employee, I quite like defined contribution pensions because it gives you more control over your pension investments. However, you can only take control of your pension pot if you know where it is.

A couple of years later after first being given the opportunity to open a pension account, the company I was working for at the time decided to change pension providers.

I imagined the transfer would be relatively simple so agreed.

But it wasn’t even a transfer! Rather, everyone in the company was given a new pension account, with a new provider.

So already, my relatively new financial life was beginning to get more complicated. I now I had two pension pots – one with my contributions to date, and a new one where my money would be going in the future.

cautionFind Your Lost Pensions

The more pension pots you have, the easier it is to lose track of them. Thankfully, the UK Government offers a free service to help you find any pensions you may have.

Click this link to find your lost pensions.

You’ll be asked to fill in a form and the service will look on pension databases to find what you may have lost.

What To Do With All Your Pension Pots

Once your total pension pots reach £10000 you can transfer them into one easy to manage pension pot, called a SIPP (Self Invested Personal Pension).

SIPPs are great, but SIPPs are not suitable for everyone.

Note that you can’t transfer active pension pots that you are currently paying into. Transferring multiple inactive pension pots to one provider is often recommended because it allows you to better understand your entire portfolio and be able to calculate your asset allocation more easily.

Eventually you’ll need to convert your pension into income, often through an Annuity. For more information about annuities be sure to read this:

Annuities Explained


{ 0 comments }

Often when it comes to saving, it can be hard to add meaning to what you’re saving for.

If you have a spending goal that you’re saving towards then it can help, but once you spend the money when you’ve reached your goal you’re back to square one…no savings.

So of course you need to have different savings accounts for different goals – short, medium and long term. 

The key is keeping these separate and not allowing yourself to ‘borrow’ for one account to fund another.

One of my favourite ways to spend money in my ‘short-term’ savings account is on plane tickets. Flying, for me at least, is a magical experience and I enjoy every second of it.

In 2012 I flew over 20 times and admit that plane tickets were where most of my money went last year!

As flying is so exciting to me, I loved hearing about the new Royal Brunei’s 787 Dreamliner from London Heathrow.

Earlier this month on Monday 2nd December 2013, Royal Brunei Airlines (RB), Brunei’s national carrier, launched a Betterfly service from London Heathrow as they officially commence the first London, Dubai, Brunei route on RB’s new Boeing 787 Dreamliner, powered by Rolls Royce Trent 1000 engines.

They are the first airline to offer a Dreamliner service from London to Dubai and on to Brunei. The addition of five modern Dreamliners to the fleet and an intention to be the first airline to offer a 100% Dreamliner service on long haul is a testament to their ambition to offer a truly personal and award winning service to all passengers.

Fares on Royal Brunei Airlines from London Heathrow start from £360 to Dubai, £695 to Brunei and £710 to Melbourne.

For me, a flight on the new Dreamliners is just the kind of thing that makes saving for the short, medium and long-term worthwhile!

What are you saving for?

Sponsored by Royal Brunei

{ 0 comments }

Can a Car be an Investment?

by Magical Penny on November 25, 2013

Wealthy entrepreneurs and rock stars often amass large collections of cars which are the envy of ordinary car lovers. Usually the collections come about due to the collector’s enthusiasm and the obvious status conveyed by an expensive vehicle, but is it possible for cars to be an investment for an owner?

Traditionally cars are not seen as investment assets due to the fact that they depreciate, and so some consider them to be money pits like yachts.

Cars come with a host of other expenses, from fuel and important breakdown cover – for which I personally recommend the AA (http://www.theaa.com/breakdown-cover/) – to mandatory car insurance to protect you from the cost of accidents on the road.”

However car prices have been fluctuating and some believe that there are ways in which both classic and modern cars can be a good use of your cash.

For investment purposes, cars will always be inherently unreliable.

They have a one off value, in that they don’t pay shares or dividends like a business investment, and this one off return will be at the mercy of market factors. So if they are to be viewed as an investment it should be in the same category as art or wine, and included in a wider portfolio for diversification purposes.
For classic cars, the HAGI Index tracks the sales of 50 collectable models and can give guidance on investment opportunities. However predicting sales values of classic cars is by no means an exact science. Factors such as the quality of restoration, previous ownership (for example if it was owned by a famous person) and also just fashion and taste can make prices vary wildly between similar models. For example, as older generations who drove and fell in love with a particular make or model pass away, that model can become less valuable.


Limited edition cars or sole surviving models can obviously be more collectible and prized than others.

What should be remembered about the classic car trade market though is that it is a world of car lovers, who buy items for their nostalgic value or their beauty. Luckily, in times of economic trouble nostalgia generally becomes big business, so selling a classic car can be a way to make money during a recession.

Additionally, investment markets for assets such as wine have enjoyed something of a boom in China. If the classic car market receives the same interest then collectors could find themselves with some valuable assets to sell.

The most important thing to remember though is that the classic car market is unpredictable and fashion plays a large part in dictating cost.

Most collectors and traders recommend you embark on buying classics out of love and a genuine interest in the vehicles, and then financial gains will be an additional benefit. So if you have always had an interest in classic cars speak to some dealers, check out the HAGI Index and remember that quality is better than quantity. Going to auctions and fairs will help you get an idea of what’s selling and what the prices are like, as well as the type and quality of profitable cars.
When it comes to modern cars conventional wisdom suggests that you will always sell the vehicle for less than you paid for it. In years gone by this would pretty much always be true, but due to price and demand increases and inflation some people are now asking near enough what they paid when selling on their car, and in some cases more.

In particular, cars with good mpg have enjoyed a boom, so the Toyota Prius, Ford Focus and Honda Civics of the world have been in demand and sellers have been able to get strong prices.

Buying a car purely for profit like this is almost certainly a fruitless strategy – however if you want to think about the long term prospects of a vehicle then looking at such trends could increase the likelihood of making a good return.

Another good strategy for optimising the sales price of a vehicle is to buy it after it has depreciated significantly in price (known as the “sweet spot”) and then sell it on before it needs maintenance. This takes a certain amount of research and knowledge, and the ability to negotiate prices, but if you know your cars it is the best way to get a good deal and maximise your return on a vehicle.


{ 1 comment }

5 Awesome Money Saving Tips

by Magical Penny on November 8, 2013

There are so many simple money saving (and earning) tips floating around the internet. You definitely would have heard things like ‘turn off the TV at the switch’ and ‘check the taps and showers don’t leak’ for example. But there’s always some that you might not have come across or thought about….here are a list of some money saving and earning tips that you can do from home, and you might even have fun doing them!


Tip 1: Sign up for a Frequent Flyer rewards program
This one works better if you’re in America or Australia were  frequent flyer programs are more generous, but it’s worth looking around for frequent flyer programs out there offering great rewards for everyday spending.  Spend enough at one chain and you’ve earned yourself free flights or other rewards.

If you haven’t got enough frequent flyer points saved for a holiday, remember you can always save money on holidays by going camping. Camping can be a rewarding experience that you can easily enjoy with your friends and family.

Tip 2: Get an awesome piggy bank

We’ve all had plenty of loose change floating around in our wallets, pockets and cars. Lighten the load by putting your spare change into an awesome looking piggy bank. If you get yourself a hip looking bank, you’re more likely to enjoy paying attention to it. Once it’s full, take it down to your local bank to convert your small change into useful money. Deposit enough money and you can even earn a little extra interest on your savings.

Tip 3: Hunt around your house for treasure

You likely have lots of books, DVDs and games lying around in your house. While they were fun at the time, you might not care for them anymore. Why not trade them in or sell them on to generate some extra cash to pay off debt or top up your savings account?


Tip 4: Use coupons as often as you can

Save printed coupons or vouchers from your local stores in a bowl or box near the front door. Make it a habit to check for coupons before going out. There are plenty of online coupon sites too such as Ebates that offer L.L. Bean coupons and other coupons for online and local stores. Check for coupons and discounts before making any purchase online or locally. Coupons can save you loads of money as long as you remember to use them.

Tip 5: Exercise with friends outdoors rather than at the Gym

Gym memberships can be expensive with long contracts that often have hidden fees and costs. Save money by doing your workout at home or in your local park. If the exercises you would normally do in the gym require equipment, research other exercises that target the same muscle groups that you can perform without them. If it’s the spin class you enjoy, get yourself a bicycle. It’s a short term spend that will save you money in the long run. Riding outdoors is a great way to see new places in your neighbourhood and is more enjoyable than stationary bikes.

{ 0 comments }

How to Know When to Take Your Business Abroad

by Magical Penny on November 4, 2013

Many companies will make the decision after a few years that it is time to venture into international markets, whereas some choose to dive straight in.

Many smaller companies do not build an export plan into their original strategy and so when it does come up, the subject is more of an afterthought. It is really important that companies don’t make the leap into foreign territory without having done the research and preparation needed.

Before you make this huge decision, read the tips provided by 4x Currency below to work out whether your company is ready to venture overseas:

 1.     Have You Got a Plan?

Before you even begin to pitch for overseas business, you need to make sure you have a plan with a strategy in place for all eventual outcomes, both positive and negative. If your attempt to export does not work, you need to have a plan to turn it around, and if you do really well, you need to know how to deal with a sudden increase in demands.

2.     Are You Financially Able?

You will need to have reserve funds ready if you plan to export, as there are many different costs to take into consideration. International clients may expect credit for longer than your domestic clients, and there will be administration costs and transportation fees too. To make this a success, it is a good idea to have loans accessible so that you make a heavy investment early on and don’t run out of money.

3.     Do You Have Your Target Market?

Don’t even think about pitching until you have clearly identified your target market. Exporting will never work if you go in with the plan to target anyone and everyone in the hope that something will work. Do some research on the markets that you are interested in, and make sure you think about all the other factors that will hit you in that area such as local business protocol, local taxes and of course, entry requirement.

4.     Do Your Management Agree?

Before making any sort of decisions, it is really important that your company’s whole management team back the plan and are fully on board. The likelihood is that there will be bumps along the way, but with a group of people backing your decision and helping out, you will be in a much stronger position.

5.     What’s Your Price?

Instead of planning to transfer your domestic prices, think about how much your target customers will be able to afford. If you are going to be exporting your service or product to developing countries, then they will not be able to afford to pay the same prices as richer countries and you may need to drop your prices.

6.     Is Your Product Required?

The last thing you want to do is enter a market that is already completely saturated with your product. Make sure that there is a genuine demand for your service or product in the area you are targeting and that the customer base you are going to be selling to will have a reason to buy it.

7.     Can You Service Overseas Clients?

You are going to need to have the technical skills required to for overseas selling, alongside the appropriate customer service levels and aftersales support. If you cannot provide these in a foreign country, then you are going to find yourself stuck very quickly. With staff that have the skillsets to meet all this necessary criteria, your business should go relatively smoothly.

8.     Is Your IP Protected?

You need to make sure that all your international property and most of all your trade mark and branding is protected in the countries you want to do business in. If they aren’t, then any other local business can register your trademark and you will have to start from scratch with a full rebrand.

9.     Do You Know The Law?

Believe it or not, your service or product could actually be illegal in some countries. Some governments will help out and protect foreign companies, but some will completely discriminate against them with the use of tariffs and red tape. Make sure you know that your business will be positively received in the market you are planning on targeting.

Summary

If you can answer “yes” to all these questions, and feel confident in those answers, then chances are that you and your company are ready to go abroad. You don’t need to be a global player to do business globally these days, you just need to make sure you know what you are doing and how you are going to do it.

Preparation is so important and doing all your research before you make a plan will mean that you have everything you need by the time to get round to making the jump.


{ 0 comments }

Do Women Wear the Financial Trousers in UK Households?

by Magical Penny on October 13, 2013


My life has changed quite a lot since I started Magical Penny.
When I started writing about money I was single, in my early twenties, and only had to think about myself (and my future self!).

These days I’m now living with my girlfriend in York and far from just thinking about myself, I need to consider my girlfriend in all my decisions, particularly monetary ones.

So when I came across new research about the dynamics of money management for couples in the UK I was certainly intrigued.

The research revealed that women wear the financial trousers in UK households – although men, naturally, disagree!

The study, funded by Go-Compare showed that over two thirds (68%) of men said they look after the finances in their homes – but 63% of women said they did too.

When it comes to managing finances, only 19% of men said they looked after the finances with their partner, compared to a quarter (25%) of women.

Women are more money aware in UK households according to the study, as 44% said they knew how much cash was in bank accounts and how much was owed on credit cards, compared to just over a third (36%) of men.

And it seems that despite having a close eye on household cash flow, women are the spenders too, with just over a third (34%) of women admitting that they spent the most in their relationship, compared to under a quarter (24%) of men who said that they were the bigger spenders.

It also seems that women don’t trust the men in their lives when it comes to money. Just over one fifth (21%) of the women surveyed confessed to opening their partner’s credit card bill and bank account statement all the time. Men are more trusting; with only one in ten (10%) saying they do the same.

In fact, just under two thirds (63%) of men said they had never opened their partner’s bank statement or credit card bill, while less than half (48%) of women could say the same.

It’s not surprising, then, that while 69% of men thought that opening someone else’s bills shows that they don’t trust their partner, only 49% of women agreed.


Money is often the cause of arguments in relationships, so transparency of finances is the best way to go (even if it can difficult and scary to share). 

I’ve still got a lot to learn about keeping a relationship positive and fun but hopefully these research findings will be good food for thought and might lead to discussions around money and better joint money management in your relationship.


{ 1 comment }

Some Sound Advice for Those Moving Home

by Magical Penny on October 2, 2013

There are few things more stressful, choresome, potentially complicated and yet nonetheless exciting then moving home. Since our homes are places we typically spend most of our time, making sure the right choices and moves are made is obviously exceptionally important. Here are some bits of advice for those moving home.
While Packing

The magnitude of packing when moving home is often underestimated. Due to its straightforwardness, packing is expected to be quick and simple. However, it is only when moving home that one realises how much possessions they actually have, while you will naturally own a number of possessions that will require special attention and care when moving home.

The last thing you should want when moving home is for your new home to be overloaded with possessions. This will only serve to create clutter within your home and also make settling in more of a chore. Use this opportunity to sort out your possessions and get rid of anything that you do not really need. Meanwhile, clothes you no longer wear can be given to charity.


Moving Belongings

When hiring a van to move belongings in, you should consider whether it might be either too small or too big. If it is too small then you might have problems fitting many things inside it, consequently leading to plenty of trips back and forth moving possessions. On the other hand, if it is too big then you may encounter problems parking the vehicle near to either of the homes, which is inconvenient for obvious reasons.

It’s usually more expensive to book vans on the weekends, and so if you can, it might be more cost-effective to move on weekdays.

Alternatively you can hire a removal company to deal with the packing and moving of your possessions. Your options when it comes to using professionals to help you move are usually quite flexible. For example, you can choose to have it all done by professionals, or do the packing yourself before hiring professionals to simply move your things. You can even do half of the moving yourself and leave the rest to the removal company, if you wish to save a bit of money.

A removal company should be hired at least a fortnight in advance of the move date, in order for you to ensure everything is arranged in time. Only use removal companies that are members of the British Association of Removers, since these are officially licensed and reliably professional. Rates are typically competitive throughout the removal company market and so you should get a number of quotes before committing to one company, in order to get the cheapest deal.

If you’re renting out the place you’re looking to move into, check to see if your landlord or landlady deals with the management of the property himself or herself, or if they use property management companies such as Rentify.

Those that use professional property rental companies are likely to be more efficient in matters regarding the maintenance of your new home.

{ 0 comments }

The Cost of Life is Rising

by Magical Penny on September 22, 2013

When I first started working in early adulthood I made it a focus to limit my spending.

I was terrified of  the hedonic treadmill that would race me to financial ruin. I didn’t want to spend money on things that would make me happy in the short term because I knew it wouldn’t last. We humans have a tendency to remain at a relatively stable level of happiness regardless of our fortunes, and purchases, so I didn’t see the point of spending money on things that would only make me happy for a little while. I ended up feeling guilty when I did spend money because I felt it would be better spent by the future self rather than my current self.

But my scarcity mindset of saving as much as I could did not last: Not when I could see how many opportunities there were to increase my earnings and spend money and still be able to save large amounts for my future. I could have it all, and for a while I did.

Until I didn’t.

Alas, the future is more uncertain and more expensive than you may think. It will always be a balancing act between spending needs and wants, and generating income that makes life possible. And this balancing act can quickly become unbalanaed as circumstances and opportunities change around you.

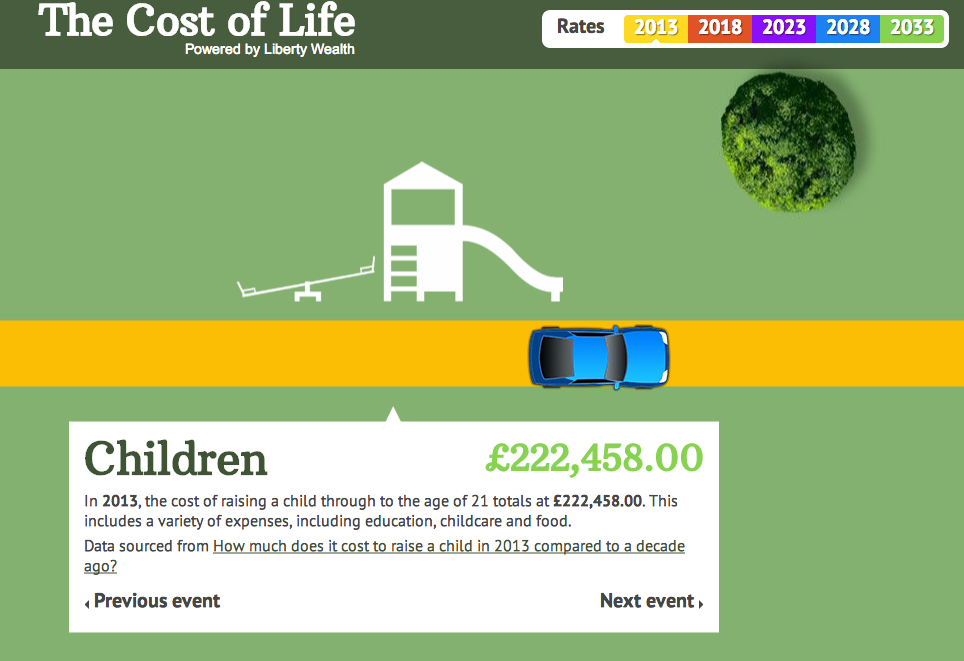
I’ve been living through a period of particularly changeable circumstances right now, so coming across this new UK “Cost of Life” info-graphic was enlightening.

The data behind the info-graphic predicts the cost of life will rise by 64% in the next 20 years!

(click the picture for more)

Based on the UK’s average inflation rate of 2.5%, British nationals can expect their biggest purchases (and the cost of raising children!) to increase by nearly two thirds within the next 20 years.

The interactive info-graphic reports some surprising and perhaps shocking projections; including the average cost of going through university which is set to increase from £88,700 to £145,000. Other major investments are also highlighted, such as the estimated average cost of raising a child to the age of 21; set to increase from £222,000 to over £364,000.

Are you saving enough for what life might throw at you?

By opening up a savings account and putting aside a little each month, the British public will be better prepared for rising costs and prices. Whether it be opening up a tax free ISA account or putting money away into long term savings, there is never a better time to start than right now.

You don’t have to be scared about spending money, like I was in my early 20s.  But you do have to walk through life with your eyes wide open about the expenses that may be up ahead, and this info-graphic provides some perspective.

Can you relate? Tell me in the comments below.

{ 0 comments }