What To Know Before Becoming A Loan Guarantor

by Magical Penny on August 10, 2016

Many people are unsure as to whether they should take on the role of a guarantor when it comes to a loan. It is important to understand the pros and cons of this position and weight them very carefully as it could impact the quality of your own life.
small questionWhat is a Guarantor?

Let’s look a little deeper at what a guarantor actually is. In its simplest form, a guarantor is someone who is going to hold responsibility for the debt of someone in case they default on the payments. Whoever signs as the guarantor of the loan is the one who is ultimately responsible for the loan to paid in full.

Visiting pages like http://www.guarantorloansuk.net will help you understand the position the loan guarantor is in before guaranteeing the loan. You may want to know what type of income they are currently bringing in and if they are already in some form of debt. This makes it more likely that the guarantor will have to pay part or all of the loan.

A bank is only going to ask for a guarantor if they are not satisfied with the financial status or credit rating of the borrower, in this sense it is important to proceed very carefully.

Why Have a Guarantor?

There are times when a bank will ask for a guarantor if they simply feel they do not have enough credit references. In fact, there are several reasons why banks ask for a guarantor.

  1. The bank may be concerned that the applicant does not have a transferable job.
  2. It could simply mean that the applicant’s job takes them out of the country for extended periods of time.
  3. The borrower might have applied for a loan and used an address other than their permanent address.

It is important to fully understand that no matter who you sign for, if they default on the loan it is you who will be responsible for the full amount that has not been paid. The bank will approach you if the debt is not paid. You must know that a bank is under full authority to seize any of your assets in order to reclaim the amount of the debt. This includes property, bank accounts, and cash, this leaves you very vulnerable to bankruptcy.

The Supreme Court has stated that once a guarantor has committed to the loan, they are unable to back out of the commitment.

In addition, your credit rating can be affected in a negative way if the payments are defaulted on. Almost all banks will check the credit rating and status of the loan that you have signed on as a guarantor. Before you will be able to apply for a new loan, the remaining amount of the guaranteed loan must be repaid. Any past due payments will also show up on your credit report which will have a negative effect when applying for credit cards and loans. In fact, it may prevent you from getting any type of loan.

Knowing all of this information it is essential that you do your research not only on the loan but the person you will be guaranteeing for. You need to know in which conditions you will have to pay back the full amount of the loan as well as if the loan amount can be increased at any time without your consent. The most important aspect to realize is once you have signed on the dotted line there is no turning back.

{ 0 comments }
7 Smart Ways to Add Value to Your Property

by Magical Penny on August 8, 2016

houseWe all want to add value to our property in ways that give a maximum return to our investment, but did you know that employing a team of excellent exterior house painters is a far better investment than that hot tub you’ve always dreamed of?
Here are 7 relatively inexpensive ways to spruce up your property from All Weather Coating and add thousands to its value.

1. Refurbish the Front Door

It’s the first thing that any new buyer sees, and it gives your house instant kerb appeal. Peeling paintwork and difficult locks won’t cut much ice, but refurbishing your door can be done cheaply and effectively.

Sand down your paintwork, and then varnish or paint. Green is the most popular paint colour in the UK, as we associate it with generosity and a warm welcome. Replace those old locks, and add some colourful tubs of flowers or shrubs or pretty hanging baskets.

2. Shine Hardwood Floors

If you have hardwood floors, you’re in luck – they’re one of the wow factors that are top of a new home-buyer’s shopping list. So make sure yours are in great shape. Clean well and use a good floor polish to bring out the natural shine and beauty of the wood.

3. Burglar-Proof

Safety is an increasing concern in our modern world. If you have the funds to invest in an alarm system, this is a selling point. But there are cheap and effective ways to burglar-proof your home that will add value for less.

Make sure that locks are fitted to all windows, exterior doors and outbuildings. A mortise lock is preferable to a deadlock in security terms.

4. Employ Exterior House Painters

One of the cheapest ways to add value to your property is to paint it. And it really is worth employing exterior house painters as they are experts to finish the outside of your property.

Consider investing in an all-weather wall coating. This has the benefit of disguising imperfections and being impermeable to rain whilst insulating your house against extremes of temperature.

Best of all, a high-quality product expertly applied minimises the need for exterior redecoration. All that and up to £10,000 on the value of your house is a great return on your investment.

5. Central Heating

house mortgage UKIf your house doesn’t benefit from central heating, then it’s imperative that you have it fitted. Central heating can add as much as 5% to the value of your property, making it a worthwhile investment for future resale and a comfortable living environment for you.
Open fires and wood-burning stoves are also increasingly popular and worth fitting if you have a suitable flue.

6. Double Glazing

We all know the benefits of double glazing – an improvement in energy- and heat-efficiency plus a reduction in noise – a must if you’re on a noisy street. If you have partial double glazing, it’s worth replacing any single-glazed windows to keep costs down.

Fully replacing your glazing can run into thousands, but grants are available through the government’s Green Deal scheme, and the market is a competitive one so look around for good deals.

With an average 10% added to the value of your house, double glazing is one improvement worth spending on.

7. Insulate Your Roof

This is another small spend that saves thousands – without adequate roof insulation, you and your buyer could be losing a fortune in heating bills.

Follow these few simple changes, and you’ll soon have a beautiful home that realises its full sales potential.


For more articles about Property check out the Property archives

{ 0 comments }


ImportantThere are a number of business leaders who read Magical Penny. Having a business is a great way to become financially empowered. However, your business is only as good as the people in it. You need to recruit the best, and often-times it makes sense to get help to do this.
However, the debate about the cost of recruitment services continues to dominate headlines. What I wonder is whether we should really be jumping on the bandwagon, or perhaps we should take a closer look into why recruitment costs what it does and its values to businesses.

I want to take a closer look at the four key things that recruiters do to create a recruitment strategy that internal departments cannot. In short a recruiter’s role is to match the right candidate to a specific job and company, as and when it’s needed. Financially making the right match at the right time can be a great asset to a business, however making the wrong match can cost a lot of money.

Here are the four areas in which recruiters can excel.

  1. Connections

Often recruiters are seen as relationship builders. The nature of their role and sector means that over time they build up a strong network and knowledge of people and connections. These include candidates, clients and hidden ‘passive’ candidates. The community of people they get to know sets them at much more of an advantage in comparison to those who work in house like hiring managers or in HR.

  1. Time

What people often forget when judging recruitment costs is that they dedicate their entire job to finding candidates. The entire reason why employers choose to use a recruitment agency is because they themselves don’t have the time to actively recruit. So not only does a recruiter’s capacity to focus their work allow them to find candidates and clients, they also free hiring managers and employers from doing so.

  1. Screening

Recruiters are involved throughout the screening process, so that means they source and handle applications, they also screen and interview candidates at preliminary stages. This means that a great amount of time is saved for the employer and guarantees only the best, well-suited candidates come into contact with them later on in the process.

  1. Research

And finally, research. It would be a perfect world should the desired candidate come to you each time you had a position to fill. That would make life and your job that much easier, but unfortunately we all know it doesn’t work like that. Finding the right candidate takes time and a lot of research. Even once candidates have been found, there are a range of other checks to run through. And this does not all happen overnight!

So with that said it may seem clearer why recruitment costs what it does. Each of these areas requires a lot of time and attention and therefore contributes to the overall price.

What I would suggest is that the means of recruitment do justify the ends, almost every time. Yes there will be instances where the candidate match isn’t the right one, and yes this can cost money. However more often than not recruiters are experts in this industry and more matches are made than not.

Take Harriet Green when she took on the role as CEO of Thomas Cook. The company recruited her via an agency even though they were verging on bankruptcy. Two years down the line and she had turned around the company’s fortunes. Upon her decision to depart in 2014 the company’s share value fell by £400m overnight.

Although Thomas Cook spent on recruitment costs when they almost had no money, you can see that these costs were the means that justified the ends that essentially saved the company from bankruptcy. This was because Harriet Green was the right candidate match.

So maybe we underestimate recruitment agencies and their ability and efforts to actually provide something in return that is worth much more.

So if you were put off by recruitment agencies, maybe you should rethink, and give them a shot. After all, they are the experts that could have a great impact on your business. Take Simplicity in Business, head to their site to view their expertise and see how they could offer you a solution today.


{ 0 comments }

money making ideasIn many ways, the forex market offers the type of investment opportunity that remains viable regardless of the wider economic climate. After all, it is possible for traders to profit even in a depreciating market, as they are able to tailor their trades and capitalise on fluctuations between individual currency pairs.
This creates a volatile and constantly changing market, however, which may not be suitable for new or inexperienced investors. In these instances, you will need to think carefully about your burgeoning investment portfolio and consider the impact that recent, socio-economic events have had on the forex market.

A Look at the Current Market: Why is it so Volatile?

So why is the forex market particularly volatile and unpredictable at present?

In short, there have been a series of events that have triggered seismic price shifts and movements, starting with the Brexit revolution in the UK. The proposed withdrawal of the UK from the European Union sent the pound plunging to its lowest value in 31 years, and while it has since rebounded it continues to perform poorly against the US Dollar and the Euro. With this trend unlikely to change while the uncertainty remains, it is hard to identify prosperous and reliable currencies at present.

There are other, localised events that are also impacting on the market. Take the decision of the Nigerian Federal Government to alter the interbank exchange rate of the naira for example, which shifted from N197 to N280 against the dollar. This has sent the cost of international airfares along Nigerian routes spiralling by an average of 54%, while also catching emerging market investors completely unaware. This type of sudden and unforeseen development is typical in the forex market, while it often leaves those who are heavily invested in a particular currency exposed.

Considering your Options as a Financial Market Trader

These events, along with the continued fluctuation of the Euro, have left the US Dollar as the only truly prosperous currency in the existing market. While this does offer an opportunity to invest and back the Dollar within a chosen currency pair, the American economy is itself far from stable and liable to fluctuate depending on key data releases.

Although it can be argued that the real-time analytical tools offered by platforms such as HantecFX equip investors with the tools to optimise their trades at any point in time, they can do little to affect the underlying rules that govern change in such a volatile marketplace.

In this respect, forex market investment may be something that is best left to knowledgeable and experienced traders in the current climate. While there is always an opportunity to profit from currency, the existing social and geopolitical climate makes it extremely difficult for novice traders to achieve their goals.

For other investing articles check out the Magical Penny archives for Investing.

{ 0 comments }

Which Debt Management Solution is Best for You?

by Magical Penny on July 25, 2016

When thinking about debt, the solution that springs to mind is most often bankruptcy. Though this certainly serves its purpose as a last resort solution, there are other options open to you that are important to consider.
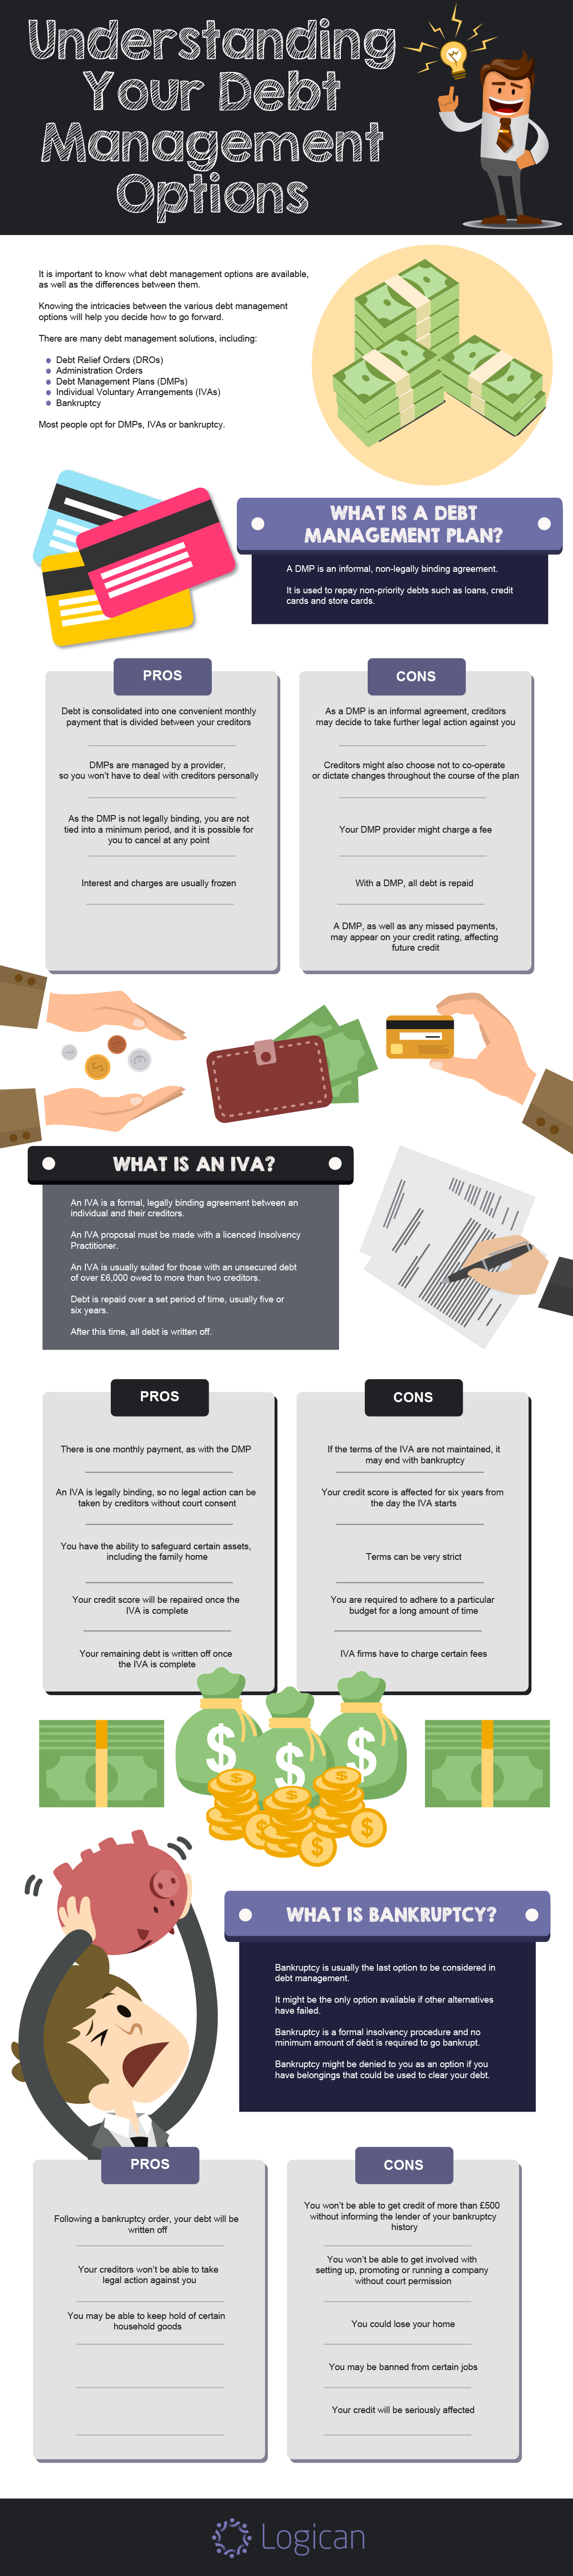
Debt management professionals will be able to help you make the final decision when it comes to resolving your debt problems. They have access to insolvency software that is used to assess your income, assets and expenditures to recommend the best way forward. They also have years of experience with insolvency and have been certified by a regulator to show that they are capable of dealing with your debt.

What options are open to me?

There are a number of debt management solutions out there, but the most popular and commonly used include Individual Voluntary Agreements (IVAs), Debt Management Plans (DMPs), and Bankruptcy. This infographic will demonstrate the pros and cons of each solution to best illustrate your options.

Debt Management Options – Logican Solutions Understanding Your Debt Management Options infographic was brought to you by the team at Logican Solutions

Is an Individual Voluntary Agreement (IVA) right for me?

An IVA might be suited to you if you are a resident of England, Wales, or Northern Ireland and you are technically insolvent. This basically means that you have the ability to repay some of your debts, but not the entire amount. In order to be considered for an IVA, you will need to be in debt to more than one creditor, and generally speaking you will be more than £15,000 in debt. For an IVA to be a realistic route for you, you’ll need to have a regular monthly disposable income.

If your IVA request is accepted, you will have to live on a very rigid budget, but you will not experience the same restrictions that you would should you opt for a bankruptcy. Once your IVA is complete, after approximately six years, your remaining debt will be written off and the IVA will be wiped from your credit report. To find out more about IVAs, get in touch with an Insolvency Practitioner, who are experts in this area.

Is a Debt Management Plan (DMP) right for me?

Whether or not a DMP is right for you will depend on a number of factors. Consider the extent of your debt. If the amount is in excess of £7,000 and comprises of unsecured debts including store cards, credit cards, and overdrafts, then this route might be right for you. You won’t have to release equitable interest over to your lenders, but as a DMP is an informal agreement, there is always a risk that your creditors might change the terms of the agreement or back out altogether.

Unlike an IVA, you will pay off all your debts with a DMP, which means they usually last longer than an IVA. If the amount you owe is far larger than £7,000, it is worth considering another option, as it will take a lot of time to repay this amount with a DMP.

Is bankruptcy right for me?

Most debt management professionals would recommend looking at bankruptcy only when you have exhausted all other options. Determine whether or not you can feasibly repay your debts in any other way. Do you have any assets you might be able to sell to repay your debt? Might your financial situation change in the near future? If not, then you can get in touch with an Official Receiver to arrange bankruptcy. All your possessions will be taken into account and potentially sold to cover your debts. When you consider the restrictions that will be placed upon you on top of this, then bankruptcy can appear a truly daunting option – unfortunately, for some, it is the only option available. There is no minimum amount required for you to go bankrupt, and like any other financial indiscretion, it will be wiped from your credit report after approximately six years.

{ 0 comments }

If you are one of the 1.6 million homeowners have bought home insurance from their mortgage lender, a new study has foundmany mistakenly believe they cannot switch for a better deal.

homeowners-insurance-resourcesThe survey by Go Compare found 30% (466,200 households) believe their home has to be insured with their mortgage lender as a condition of the loan; and that 6% were told by their lender that it was a mandatory purchase. Nearly a quarter (24%) think switching away from their lender’s insurance will invalidate their mortgage.

 Worryingly, 12% said they felt under pressure to buy their lender’s home insurance.

Protecting a property with adequate buildings insurance – typically against fire, flooding, subsidence and storm damage – is as a requirement made by all mortgage lenders.  Buildings insurance provides financial protection for the borrower (and ultimately the lender) from damage to the main structure of the home.  While most lenders offer home insurance, borrowers are not obliged to buy it for them.

The practice of compulsory home insurance tied-in mortgage deals was never formally outlawed despite promises to do so in the late 1990s.

Whether you are arranging your first mortgage, re-mortgaging your home, or a long-standing mortgage-holder, you can shop around for your home insurance to find the best deal.


home insurance in the UKWhy buying mortgage lenders’ home insurance might be the wrong policy
The survey also revealed that just over a third (34%) of homeowners who arranged cover through their lender didn’t check cover levels and excesses to make sure they were buying the right policy.  According to statistics published earlier this year by the Association of British Insurers, the main reasons for household insurance claims being rejected included the claim value being below the policy excess and the incident not being adequately covered by the policy.


If you have a mortgage on your home, then your lender will require you to protect your property with buildings insurance.  But it’s up to you where you buy that cover from.

As well as finding a good value policy, you also need to make sure it covers all the things that are important to you, plus any minimum cover levels your lender may require, and comes with excesses that you can afford


{ 0 comments }

The Worrying Rise of Forex Scams and How to Avoid Them

by Magical Penny on July 20, 2016

warning explanationThere has been a small rise in certain parts of the world recently of forex scams appearing, attracting victims and leaving them in a worse financial position. Malaysia seems to be a hotbed of forex scams, with many young people in their 20s and 30s falling prey to them throughout 2016.
It’s easy to see why so many people get caught up in them, with promises of making huge profits through a get rich quick scheme. However, if you want to be a serious trader or investor and genuinely improve your finances, avoid them at all costs.

Recent Forex Scams

Unlicensed forex service companies have been signing people up to invest in offshore forex companies with promises of fast returns. Many operate on a multi-level marketing method, making money from registration, recruiting and forex investment fees. When the ‘company’ has enough money it then closes and disappears.

Being offshore means it is nearly impossible to legally prosecute any of them. This has led to calls for fresh measures to tackle forex scams, especially in Malaysia where many young people are borrowing from friends, families and loan sharks to sign up.

How to Spot One

A forex scam can easily be spotted by the terms that are offered seemingly too good to be true. Often this is because they are! While forex trading does involve a lot of risk and there is a chance of making large profits, it will not be done overnight.

Any supposed forex company promising a get rich quick scheme is probably lying and just after your sign-up fee. Even the most successful traders will have spent years building up their skills and wealth through the practice. There are no get rich quick schemes that actually work, especially in forex given the small margins between currency values.

Avoidance Tips

In order to avoid being roped in by a scam, the best advice is to trade through a regulated, professional platform. Other tips include:

  • Google the product/scheme – shows any problems others have experienced
  • Check the firm online – visit the website, LinkedIn profiles of staff to ensure it is legitimate
  • Talk to people – ask experts if they are aware of it and reputation
  • Try a demo account
  • Regulation – find the forex regulation body and see if it is listed

These should all help you avoid being scammed when starting out on what will hopefully be a successful forex trading career.   

{ 0 comments }

Saving moneyWith governments and political parties constantly in flux, dealing with foreign currency is a major risk for investors.
Despite the risks involved, dealing with foreign currency can be hugely profitable and financially beneficial if you know how to do it right. Here’s how to minimize the risks of dealing with foreign currency:

Economic risks

By far the most real threat to your foreign currency is economic change. Although you can’t always be prepared for everything that happens when it comes to the economy, one way to prevent significant risks is to keep up with current affairs. Things like the recent Brexit and government decisions across the globe impact hugely on the value of currency, meaning that by staying in tune with current affairs and global politics, you should be well informed of any drastic changes coming into effect and be able to plan a contingency strategy well in advance. Companies like Ebury, help companies to minimize the risk by offering a flexible credit facility.

Diversify across the globe

Spreading your assets across many different regions is a sensible way to mitigate risk. By no longer having all your eggs in one basket, or one currency so to speak, you’ll be able to be sure of a certain degree of financial security thanks to the variety of different currencies that are available across the globe. Currencies that are tied to the US Dollar always tend to be much stronger, with many foreign currencies fluctuating. The Brexit hugely impacted on the value of sterling in the first few hours, with in dropping to the lowest it had ever been in over 30 years however as the days went on it slowly has increased again. The unpredictable nature of the situation highlights just how important it is to spread your assets across different currencies.

Invest in currency hedged funds

Hedging involves taking one risk to offset another and can be one of the best ways to reduce risks. This is the best way to mitigate risk if you’re very active when it comes to investment. By hedging you’ll constantly be making the most money from your investments, that is if all your moves are the right decision.

Dealing with foreign currency is always risky due to the nature of the world and the unpredictability of governments. However, by following these tips you’ll be able to minimize the risks for a more profitable investment.

{ 0 comments }

Where to Find the Best Savings Option for You

by Magical Penny on July 14, 2016

Having loads of money can be a real burden, can’t it? While it’s sadly not a problem many of us experience, there will hopefully come a time when you start to develop savings that require more attention than just being left sitting in a current account, for you to dip in and out. If you’ve started to build up a decent amount of savings and are wondering what to do with them in order to help them grow, then be sure to consider the following options and weigh up which is best for your financial situation and needs.


Why Being Bad can be GoodSavings Accounts

Anyone serious about saving will likely start with a savings account. Many banks and lenders will have a range of different savings account options available.

Pros

Putting your money into a savings account is a safe and secure decision, as all respectable credit unions and banks will be insured. Therefore, even if there is another financial crash, it should be safe. You’ll also have access to the funds at any time and most accounts can be opened with a small initial deposit and no requirements to continue depositing certain amounts.

Cons

Compared to some other savings options, most savings accounts have relatively low interest rates. This means it will take longer to increase your savings. Depending on the lender, there may be a minimum balance amount that must be adhered to as well, with charges enforced if your savings fall below this.

ISAs

Since they were first introduced in 1999, ISAs have become a popular saving method for a lot of people, with many variations from help to buy to tracker ISAs available.

Pros

One of the main benefits of all ISAs is that they are completely tax-free. This includes all the interest gained on them, no matter what your income. Some fixed-rate CASH ISAs have higher interest rates than the instant access or easy-access kind as you must leave your savings in the account for a set amount of time, often at least one or two years. You can save up to £15,240  in an ISA.

Cons

For some, that figure may be a negative if you have plenty of spare cash to save, as it is the maximum that can be split across various ISAs too. If you do need to withdraw then expect to have the interest rate slashed or be charged. If you do withdraw from an ISA, you can now put that money back into the ISA without it affecting the annual allowance, as long as it is before the end of the tax year in which you made the withdrawal, which ends on the 5th April each year. For example, if you put in £15240 in May, you could take it out and put it in again, as long as it is before the 5th April of the next year.

Investments

ProfitThose who are willing to take a little risk to increase their savings should consider putting some of their savings into investments.
Pros

A much higher return on investment can be gained through investments. Depending on how much of your savings you decide to invest, and the success of where it is placed, it can be incredibly rewarding. It can be a more exciting way to use your savings, as you take full ownership for each investment.

Investments can go in a Stocks and Shares ISA – when an investment is in an ISA all the gains are tax free -you never have to pay any tax on the funds when you access the money.

Cons

There is a lot more risk involved and the chance that your investments value might have gone down at any time.  There is a risk you could end up with less than you started with, so only invest money in investments when you have many years before you might need the money, to give it time to grow and recover from any losses.

Consider all the pros and cons of such savings choices before investing your spare cash in any of these options.

If you’re new to investing, have a read of other investing articles on Magical Penny by clicking here

{ 0 comments }

Why Did Precious Metals Soar in Price After Brexit?

by Magical Penny on July 13, 2016

investing for the futureIn the hours following the Brexit result being announced, the price of gold was one of the day’s main winners as it soared by over 20%. Precious metals as a whole all had a successful time as they increased in value, due to the UK voting to leave the EU.

The markets have calmed down a little since those crazy first few hours and days, but the price for many precious metals still remains relatively high, especially compared to pre-Brexit levels. There are a number of reasons as to why this price hike occurred, that can be used in predicting future price changes.

The Safe Choice

Buying gold is traditionally a safe haven option for many traders and investors when market risk is significantly ramped up. Once a sense of panic set in as the result was confirmed, many took their financial investments in stocks, shares, bonds and more and moved them over to precious metals.

For many the aim will have been to move it over for the short term until the markets have returned to normal and are more predictable. Uncertainty in the markets always leads to precious metal boosts, specifically in gold as it provides better returns on investment than any other risky options during such times.

An Unexpected Result

The Brexit result was also unexpected by most people, which led to fewer investors buying into precious metals as a safety option before the referendum. Instead, many were happy to keep their stocks and other investments where they were, until the relatively shock announcement that the UK had voted to leave the EU came through.

Due to many investors expecting the UK to remain, they were caught off guard and ended up buying into gold and other precious metals as soon as the result was announced. This is one reason the price jumped up by so much so quickly.


Silver’s Surprise

While gold was the precious metal most were focusing on, it was actually silver that experienced the biggest gains in reaction to the Brexit. Gold was always predicted to do well as a popular safe haven, but silver surpassed all expectations.

It was up 45% in dollar terms and 65% in sterling, reaching its highest level in two years. Safe haven demand, the US Federal Reserve not expected to raise rates and the Bank of England and European Central Bank stimuli, all worked together inadvertently to create the rally. Plus, lower interest rates reduced the opportunity cost of holding such precious metals, making it a more attractive prospect.

What Next?

Some investors may have just bought into precious metals as a short-term, safe haven choice, with the intention of selling sooner rather than later. However, other investors believe the rise in price has legs and will last into the future.

With the fallout from the Brexit yet to fully take place, a lot of uncertainty surrounding the markets remains. Gold and silver have both been on an upward trend this year too, with the Brexit representing a sharp rise that may well level off. Precious metals look set to soar in value again once Britain actually leaving the EU gets underway.


{ 0 comments }