drivingRecent statistics show that motorists are beginning to make the switch from petrol and diesel to Alternatively Fuelled Vehicles, but this has only recently started to occur and electric vehicles have been somewhat of a rarity on roads up until this point. The Government’s clean air plans certainly play a role in this, but it is also because electric vehicles are just beginning to overcome a number of hurdles that have stopped people from switching before.

Infrastructure

According to OVO, the main reason why people have been hesitant to make the switch is the lack of charging points. Whilst it is true that previously this has been an issue, the survey from OVO revealed that people underestimated just how many charging points there are. On average, it was thought that there were only 2,812 charging points but there are actually well over 13,000. Additionally, the number is rapidly rising each month and it is thought that they will outnumber petrol stations by 2020.

Battery Life

Battery life has been another issue that manufacturers have overcome. The technology has come on leaps and bounds in the last few years, and now these vehicles can travel much further on a single charge. The range is around 90 miles for a smaller battery, and all the way up to 335 on a large one. Additionally, the increasing number of charging points makes this less of an issue.

keysCost

Cost is the final issue that has stood in the way. These vehicles can be very expensive to buy, but there are many new models on the market which are more affordable. The most affordable is around £14,000, but it is worth keeping in mind that motorists can benefit from a grant of up to £4,000 for making the switch.

Value

Electric automobiles will prove to be good value for money in the near future too. You will pay around quarter of the price per mile, which will see motorists make huge savings on running costs. In addition to this, motorists will benefit from having no road tax and no congestion charges if you drive in the capital. This means you can quickly recoup the costs spent on the vehicle and save a vast amount over the years.

Electric vehicles have had to overcome a number of hurdles in recent years, but it seems that they are now beginning to do so and motorists are starting to make the switch. This electric car revolution will help motorists to save money, but it will also help to save the planet.

{ 0 comments }

What Influences the Value of the U.S. Dollar?

by Magical Penny on December 11, 2017

Saving moneyTo take advantage of upward and downward movements on currencies, it’s crucial to use foreign exchange brokers such as the well-known online platform, UFX. It enables you to trade on major pairs such as the EUR/USD, minor pairs like the GBP/CAD, and ‘exotics’ such as the USD/SEK, whose availability depends on current levels of liquidity.

The U.S. Dollar (USD) is the most used and traded currency in the world, as confirmed in the last “Triennial Central Bank Survey” from the Bank of Settlement (BIS): “The US Dollar remained the world’s dominant vehicle currency. It was on one side of 88% of all trades in April 2016, up slightly from 87% in April 2013”.

To make sure you are fully prepared to trade the USD, you first need to know what factors influence its value.

#1 Fed Decisions

 Central Banks are the most influential actors in the FOREX market, as they are the ones determining the cost and availability of money in national economies. The US Federal Reserve, known as the Fed, is the U.S. Central Bank, which decides on monetary policy that is applied across the country.

When the Fed tightens its monetary policy by increasing interest rates, reducing quantitative easing programs, etc., it means that the value of the U.S. Dollar is likely to increase. This means that more foreign investors will be attracted to the greenback, as it will provide higher interest rates than those offered in most other developed countries.

 sell buy small#2 Important Economic Statistics

 Key economic and financial statistics also affect the USD in relation to future Fed decisions. The Fed has a dual mandate of price stability (a PCE index of about 2%) and full employment, meaning a median unemployment rate of about 4.6%, both of which are crucial factors in the country’s growth.

Consequently, figures which demonstrate how close the Fed is to achieving its objectives are seen as vital for investors, as they provide clues about its future decisions. Among the most important to follow are the GDP, the ICP and PCE, the monthly employment report, and the JOLTS.

 #3 Market Sentiment

 Finally, market sentiment and psychology play huge roles in how a currency evolves. If a majority of traders believe that the U.S. President or the Fed Chair is struggling to deliver on their objectives, this often affects growth outlook, making traders more likely to sell the USD and buy other currencies with more potential to generate profit.

When trading the USD, keep these 3 points in mind, stay on top of news announcements, and choose a broker that gives you great market opportunities to take advantage of in order to trade successfully.

Note: Trading requires a very different skill-set to simply investing over the long term, and is much more risky. If you’re interested in learning about investing more generally, you can read other investing articles here on the site)

{ 0 comments }

investing for the futureAre you thinking of investing some money in a small business?

It can be a good way to get started as an investor and eventually see your money multiply but it won’t be plain sailing. It could even turn out to be a complete disaster for your business if you make the wrong moves; that’s what you should be looking to avoid. Before you decide whether or not to take up an investment opportunity, there are a few things you should be considering and looking into.

Find Out Whether the Market for the Idea Truly Exists

There needs to be a market for the products or services that a business is offering to the world. This is the most fundamental aspect of assessing a business so make sure you consider it carefully. Without a clearly defined market and target demographic, the business clearly won’t go far at all. Don’t just listen to what the company itself is saying about this; take it upon yourself to asses the market too.

Consider the People

When all’s said and done, it’s the people who make a company what it is so you shouldn’t invest in a company if you don’t believe in the people who are currently in charge of running it. Meet them and speak to them about what their aims are for the business and assess how competent they are at what they’re doing. The human touch always matters so don’t underestimate it.

Look at Their Production and Distribution Processes

You can tell a lot about a company by how it produces and distributes the products it sells. You want to see strong and efficient processes already in place because these kinds of things are the foundations on which successful businesses are built. Look for lean manufacturing processes and up to date distribution methods. The business needs to be able to cope with the demands of the modern world.

What Are the Requirements?

What will you be expected to contribute when you invest? Or more accurately, what will the company need in order to succeed? There is no sense in getting involved with a company if it needs the kind of vast sums of money and expertise that you aren’t able to offer. It would be best to leave that kind of investment to someone who is better suited to it. Know what your limits are and stay within them.

Stay Away From Novelties

If something seems like it’s nothing more than a nice novelty that could be popular now but maybe not in six months time, you should think twice about investing. Novelty products are inherently short-term and your investment strategy should always be long-term. It’s easy to get caught up in the popularity of a certain idea or type of product but always ask yourself whether it has a future before investing.

Every business is different and whether or not you should invest in a given business will depend upon many different things. You can’t expect your investments to turn out well if you don’t assess them properly.

{ 0 comments }

sumup3If you’re running a business, whether small or big scale, it’s important to make it easy for your customers to pay you.

For online transactions Paypal has made it easy, but for in-person transactions, many businesses, particularly if they are small, still only accept cash, and it’s hurting their bottom line.

How many times have you wanted to buy something from a small stall or shop only to be told they don’t accept card but you don’t have any cash on you?

It’s happened to me a number of times and those businesses have lost out on a transaction. Sometimes I run to a cash machine and come back, but often I don’t.

And I’m sure I’m not alone.

No Excuses

These days there is no excuse for a business not to offer alternative ways of paying for something, including taking card payments using increasingly accessible point of sale payment technologies like card readers.

Card readers used to be expensive, with retailers having to pay high fees for startup costs, and high fees on every transaction. Even a low cost swipe machine could cost between 3% and 4% per transaction. But technology and provider offerings such as mobile card readers are getting better all the time.

The Future Is Here

Modern chip-reading machines that can recognise Europay, Mastercard, and Visa cards are becoming more accessible, and cheaper too.

My friend has a drum shop and his whole business is run from his tablet and a mobile card reader. It’s so simple and easy for him and he’s not chained to his desk with a bulky till.

sumup2 Introducing SumUp

One of the most innovative card reader companies I’ve come across is called SumUp. They offer mobile card readers for businesses and make it really easy to get started.

There’s no paperwork to fill in and no termination fees either.

They simply take 2.75% of every transaction, which is a lot cheaper than other solutions.

It is so easy to set up that I can imagine even a child’s lemonade stand could use a mobile card reader to take payment from customers!

Not only does using a mobile card reader speed up the transaction time (no more counting out coins), but it makes the accounting and security side of handling money so much simpler.

SumUp even has a free app and reporting tools to make analysing your transactions and recording revenue much easier compared with having to handle cash.

It’s also good for the customer too.

With the increase of contactless enabled cards, transactions are more frictionless, your customers can easily pay for what they need in the blink of an eye and be on their way. They might even spend more than they might otherwise have done as they are not limited by the cash they have on hand.

sumup 1Card readers aren’t exactly new, but having a mobile card payment option like those offered by Sumup is allowing business owners of all sizes to do business anywhere.

Just think of the possibilities.

  • You could sell smoothies in the park and accept card payments straight away
  • You could sell your coaching services at a conference booth and get clients to commit to your offering right there and then
  • You could even ask your friend to pay you that money they owe you straight away and they won’t have any excuse

Take your business to the next level by allowing customers to pay with their card or their contactless enabled phone from anywhere with a mobile card reader.

With the payment side sorted, you will be able to focus on what really matters in business – serving your customers and clients – and doing that will take your business to the next level.


{ 0 comments }

small questionHow many different pension pots have you got?

Do you know how much is in each of them?

And are you saving enough for the kind of retirement you want?

If you have ever worked for an employer, it’s likely you have a pension fund of some kind. In the UK it is now the law for an employer to provide a workplace pension as part of ‘auto-enrolment’.  But it’s been a long time since the days when a worker was likely to stay with their employer for their whole career and receive a gold watch and a generous pension to keep them fed and warm in their retirement years.

The younger generation are much more likely to job-hop as the rate of change in the world accelerates and new opportunities are searched out.

In many ways this is a positive thing but it can lead to people finding they have lots of tiny pension policies, one from every employer they’ve ever had, so it’s no surprise that many of us haven’t been able to keep track of our pension plans over the years, and this could be a very costly mistake.

Looking through the details

I work in financial planning and spend a considerable amount of my working life digging through pension policy statements and valuations, making sense of what pensions and investments our clients have, and whether or not it’s worth consolidating the pensions into a single arrangement. I’ve seen first-hand what a mess a lot of people’s pensions are in, and not everyone can either afford a financial planner, or needs a financial planner to sort out their pensions.

Thankfully there’s now an easy solution, but first let me share my own my own pension consolidation experience.

How I brought my pensions together

I didn’t even have to move employers to end up with two pensions. After university I got a job and began making regular pension contributions. After about two years the company changed the pension provider they used and asked us all to sign new paperwork. I agreed to the change but in my naivety I assumed the pension scheme I had been paying into for the past two years would be transferred to the new pension scheme. But this did not happen. My new contributions along with those from my employer went into the new scheme from that point onwards, but my old scheme was left in place. I continued to receive yearly statements through the post, but no more money was going into that first pension. Half a year later I moved companies and another pension scheme three-fingerswas opened for me.
If you’re keeping count, that’s three pensions already, each with only a few thousand pounds in. You can imagine how this could get increasingly complicated over a few decades of work.

After I made my career change into financial planning and became experienced with pensions and investments I decided to take what I had learned in my day job and switch my own pensions into one scheme. Not only would I single-handedly save a tree or two in the rainforest by reducing the amount of paperwork coming through my letterbox about my pensions, but it would be easier to keep track of the value and assess the investment mix.

The process wasn’t particularly difficult in my case, especially as my pensions were simple ‘defined contribution’ pension schemes with no guaranteed benefits, but even as someone who does this type of analysis in my day job, it was still a bit of a hassle getting it all worked out. That’s why many clients in my financial planning day-job pay me to do pension reviews. But you don’t always need a financial planner to consolidate your pensions into one place for better clarity and easier administration.

pension bee reviewEnter Pension Bee

Pension Bee provides an easy way to consolidate your existing pensions into one easy to manage pot. You provide your pension information and PensionBee sorts out the transfers bringing all your pension pots together under one roof with the same consistent charges and investment choices. You can then keep up to date with the value of your pension and add to it when you’re able to.
ImportantWhat to do before you consolidate your pensions:

Before you consider consolidating your pensions it’s important to check if there are any valuable benefits attached to your plan. Phone up the pension companies and ask them what type of pension you have. Ask them if it is a standard ‘Defined Contribution’ pension – if so then great as they are the simplest and most worthwhile to switch. It’s likely you won’t be able to switch the work place pension you’re currently paying into but as soon as you leave your job and the pension becomes ‘paid-up’ you can move that pension at that time.

Whilst you are on the phone with your pension provider, ask them for a summary of the charges. (If your total charges are over 2%, then that’s expensive. Also ask if there are any guaranteed benefits attached to your pension. Examples of benefits are “guaranteed annuity rates”, and “guaranteed minimum pension”. You also should ask for both the current value and the transfer value. If the two figures are different there might be a penalty for moving your pension, in which case it would be wise to speak with a financial adviser. Similarly, if you have a “with profits” policy you also need to understand if you are eligible for any bonuses that may be lost if you transfer away.

Once you have the information about your pension and you’re satisfied your pension does not have any valuable guarantees, it is likely to be appropriate to consolidate into one easy to manage plan, such as the one provided by PensionBee.

PensionBee does all the hard work of consolidating your pensions

They also tell you about any guarantees they find (but I still think you should do this yourself too with a quick phonecall).

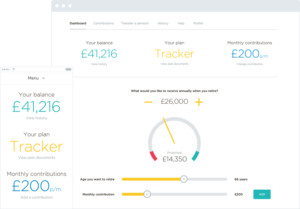
PensionBee also allow you to easily view the value of your new pension using their online dashboard – this is actually impressive and lots of pension providers don’t have online functionality even in this day and age!  PensionBee also allows you to easily add to your pension and watch it grow.
fee cost pension beeWhat does it cost?

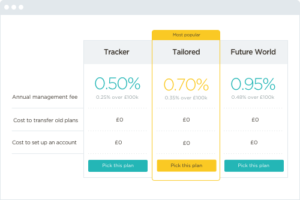
The charges are reasonable:

  • The ‘Tracker’ plan is 0.5%,
  • Tailored is ‘0.70%’
  • ‘Future World’, an ethical focused plan is 0.95%

And customers with pensions  larger than £100,000 will pay half the fee on the portion of their savings above this amount (0.25% for Tracker, 0.35% for Tailored, and 0.48% on Future World)
For example, and in contrast to competitors, PensionBee only charges one annual fee, so a customer with a £250,000 pot could only pay 0.35% per year.

Most of the pensions I come across in my day job are more expensive than this.

I admit there are slightly cheaper options around if you want to spend more time managing your pension yourself, but if you’re not inclined that way, PensionBee is an excellent way to get re-engaged with your pensions and simplify your arrangements. This is beneficial because it will allow you to know how prepared you are for retirement and if you’re not on track you can make the necessary steps to improve your financial life.

To this end their handy pension calculator can also help you discover how much you should be saving.

One thing to remember: PensionBee does not provide financial advice so using the service means taking things into your own hands. If you transfer a pension with a valuable benefit and then believe it was a bad idea, you can’t complain to anyone, as you would be able to if you had received regulated financial advice.
dashboard-combinedI’m happy to share my thoughts about PensionBee because it fits a gap in the market.

For those with big pensions and who can afford financial advice, financial advisers can add a lot of value, but for those with only a few more modest pensions, paying for advice is not always worth it.

For those who want to be really hands-on with their pensions and do their own management, there are cheaper options than PensionBee but it means lots of research and phone-calls, and that can be intimidating or just plain boring for people who don’t have the desire or experience to navigate the world of pensions and investments.

So if you have a few lower value pensions and want to simplify your life then a service like PensionBee is brilliant at cutting out the hassle-factor and helping you get engaged with your pensions in an easy and transparent way.

This post has been written in collaboration with PensionBee who are authorised and regulated by the Financial Conduct Authority. With pensions, your capital is at risk. The value of your pension with PensionBee can go down as well as up and you may get back less than you started with.
{ 0 comments }

Eye-ing Up Savings On Contact Lenses

by Magical Penny on November 10, 2017

AdamWhen was the last time you shopped around for contact lenses?
I’ve been wearing contacts for 10 years now.

When I first had the courage to try contact lenses I felt my life had been transformed. I had never felt comfortable wearing glasses, which I started needing in my early teens. In the space of six months I needed glasses and braces and my face broke out in hundreds of spots. I felt like I was falling apart, and my childhood was over.

I continued to feel self-conscious throughout my teens and even going into my 20s.

Life Changer

When I decided to try contacts it was a total life-changer for me. I was in my early 20s and finally I felt my confidence grow. The monthly cost was noticeable in my budget but worth every penny. But that didn’t mean I wasn’t going to shop around.

At first I opted for monthly contacts because they were cheaper than dailies but given my clumsiness, I damaged quite a few lenses mid-month, or even at the start of the month, so after a few months I switched to dailies – more expensive than monthlies but less hassle and, for my clumsy self, actually saved me money after factoring in the accidents!

shopping tips for supermarketsSearch for Savings

As I was looking to save money on every-day expenses I searched for ways to reduce my outgoings, including my contact lens and I tried a few different online stores for my contact lenses. I was quite pleased with myself for saving money – you can save £100s by from buying contact lenses online – I found the cost of a pack of daily disposable contact lenses from the high street is significantly higher than online brands.

Top Tip: There’s a great chart here to find out what the high street brands really use to help you find a cheaper version.

But I still had to go to an optician for an eye-health check (particularly important for contact lens wearers), and a sight test. When this was factored in, I found the monthly schemes offered on the high street can be competitive – my ‘all-in’ cost of contacts, health checks and eye tests were cheaper each year compared with what I could find buying cheap contact lenses online and then having to pay for the sight-tests on top – at least when I was first looking…

Keep Shopping Around

However, this isn’t always the case so shopping around still has merit, especially if you can find a discount code online. One that I’ve found recently is from Vision Direct, where you get 10% off your first order with the code SURPRISE (plus free postage when you spend over £49). You can find more information here.

ImportantIt’s definitely worth crunching the numbers yourself to see if you can save money.
There’s other things to consider in your own calculations – I live in England so have to pay for my sight tests, although I have friends in Scotland who tell me their tests are free for them so their total costs are different to mine.

Also some employers pay for sight-tests for their workers or allow you to claim for contact lenses and sight-tests using a health insurance benefit, so if you wear contacts, make sure you run your own numbers to work out the true cost.

Contact lenses have changed my life and the confidence they give me is priceless…but that doesn’t mean I should ignore the costs and what is available.

And neither should you.

And regardless of where your contact lenses are sourced, make sure you keep up with the health checks and eye tests – professional opticians provide a valuable service and can even save your life – for example, the onset of diabetes is often first spotted by an optician as the evidence of high blood sugar can be seen in your eyes.

When it comes to contact lenses, do your research with your eyes wide open, and see what you can find!

{ 0 comments }

bitcoinI bought my first Bitcoin in 2013 (and I blogged about Bitcoin here)
In fact I bought two coins, for £50 each. At the time of writing those two coins would be worth over £10,000. Unfortunately I was going through a career change at the time and sold them to pay for a financial exam. But I reinvested in June and already the value of a Bitcoin has doubled since I bought back in.

And now there’s speculation that Amazon will be accepting Bitcoin for transactions soon – adoption by Amazon and futures traders would push Bitcoin’s value to five digits argues David Jinks, Head of Consumer Research at e-commerce fulfilment experts ParcelHero

There’s no getting round the fact that many cryptocurrencies originally grew in value because of their use buying on the dark web.  Larry Fink, CEO of BlackRock, has called bitcoin an “index of money laundering.” But increasingly major digital currencies such as Bitcoin and Ethereum are turning away from the Silk Road on to the path of respectability.

There’s a good reason for this.

Few Bitcoin owners are actually spending their digital currency today, whether on drugs or household appliances! The majority see it as an investment. And the more mainstream a digital currency becomes; the more it will gain in value. With the value of a Bitcoin soaring to over $7,000 at the beginning of November it’s not hard to see why.

In October rumours that Amazon would finally relent and accept Bitcoin, perhaps making an announcement in their October 26 Q3 results meeting, helped drive up the value of a Bitcoin to a then record $5,800. The speculation was fueled by a global petition on Change.org, urging ‘Amazon.com should accept Bitcoin and Litecoin cryptocurrency as payment methods ASAP’. Investors such as James Altucher, the American hedge fund manager and venture capitalist, stated: “I’m certain that Amazon will accept Bitcoin. They have no choice. And this will be the tipping point that will create massive generational wealth unlike we’ve ever seen before.”

Pundits are now holding their breath for Amazon’s annual results meeting, due early February 2018, to see if Amazon finally does decide to take the plunge. And as the respected website The Next Web speculates: ‘If the mere rumor of Amazon accepting cryptocurrency can cause value to rise by thousands of dollars in mere weeks, imagine what the outlook would be if it turned out to be true.’

 The basic truth is Bitcoin investors are yearning for respectability and for more retailers to accept the currency. Why? Not to splurge their hard-earned satoshis on Kindles and Wii Switches, that’s for sure. No, the reason is that, with a bigger user base, the price of Bitcoin will both rise and become more resilient.

And if we accept the fact that digital currencies such as Bitcoins are more investment than coinage, then the latest rise in value to $7,000 is only to be expected. The U.S.-based exchange CME has said it would introduce bitcoin futures contracts this quarter, subject to regulatory approval.

 “We’ve been working with the regulator. They understand our application. And they understand our model very, very well,” Terry Duffy, CME Group chairman and CEO, told CNBC.

And the reason that announcement has so boosted Bitcoin’s value is that the introduction of such a product could bring more institutional investors into the market. And that will certainly boost the price yet further.

 Why? Because, just like gold, the amount of Bitcoins is finite. Only 21 million of them will ever be issued—and we are already at 16.3 million. Respectable institutional investors are becoming attracted to a currency that is outside any national regulation or interference: and the value of the existing Bitcoins will rise as its respectability rises.

You can read about why Forbes fintech expert Roger Aitken believes its time for investors to join the cryptocurrency party here.

As for me, I’ll share more of my Bitcoin adventures in future posts. For now, I urge you to only invest what you can afford to lose, and do lots of reading so you understand the space before you put your money in.

{ 0 comments }

5 ways to Save money at home with your bills

by Magical Penny on October 25, 2017

You may find that after paying your cable bills, cell phone bills, utilities and car insurance, your budget reduces significantly.

Spending and saving moneyThis may be because things get expensive with time and you may feel that you cannot do anything about it. However, this should not be the case if you follow a simple guide to lower your monthly expenses and help find the cheap deals out there. Saving money is actually easier when you may think when you take time off to do research on some of the areas that eat heavily on your budget. Finding ways to start saving on some of your biggest expenses such as insurance, television, utilities and cell phones can go a long way in ensuring you save from hundreds and maybe even thousands a year. These simple tips will assist you in saving money by budgeting better, without necessary sacrificing on your lifestyle.
1. Television expenses

Television has become a major pastime for most people. However, while everybody loves watching their television, satellite and cable TV accumulate a lot of expenses. This is why it is important to think about how use your TV. This will allow you to trim on expenses. A good way is to look for TV deals that cut on costs by comparing on sites like Broadband Choices. If it is possible, you should shop around for cheaper deals and negotiate when you can. Optionally, you can opt for antenna TV and combine them with movie rentals or online streaming services to satisfy your entertainment needs, you can sometimes get these joined with your broadband also.

2. Telephone bills

Mobile Phone spending

Data and texting plans may take up most of the budget allocations, and if you can find better plans, then you will trim down on your expenses heavily. It is important to closely estimate on how you use your phone and data to ensure the plan you choose closely reflects on your usage. This will reduce the likelihood of paying for plans that you do not use. Furthermore, you may also opt to change your phone and data usage habits if you find your phone bills eating too much into your budget. You can also download apps that track down on your usage habits to help you scale back on your usage. It is highly recommended to pay close attention to the plan you subscribe to, and ensure you are only subscribing to what you need.

3. Rent

Since shelter is one of the basic needs, it will probably take up the largest portion of your budgetary allocation. While there is not much you can do about rent rates, you can always negotiate with your landlord for better deals. It is also important to consider similar apartments in your area to see if you can get a good deal. In addition, you should consider the utility expenses you incur such as water and electricity. These have the potential of skyrocketing your budget allocation. You may also find it necessary to invest in a programmable thermostat. This device has the advantage of adjusting temperature automatically, which is a great way to reduce on your energy consumption.

4. Insurance costs

This is another area where you can also reduce your expenses significantly by investing in a smart plan. One way to make substantial savings is by bundling your homeowner and auto insurance with a single carrier. You may also find that making upgrades to your home such as installing a home security system will reduce your insurance costs significantly in the long run. Furthermore, you may also find it necessary to look for other insurance plans and compare to see if they are a better option from what you already have.

5. Credit Cards

Using credit cards

Credit cards do not appreciate in value, and while it may seem difficult to save on balances, there are some ways you can cut on your interest rates. While applying for credit cards, you will need to find one that charges lower interest rates. You may also want to consider credit cards that give rewards. Some credit cards will come with hidden costs. Thus, it is highly advisable to contact your provider and ask to know if there are any costs you may not know about. Furthermore, you can always talk to your provider and seek for advice on how you can make savings when using your credit card.

Check out more smart spending articles here on Magical Penny

{ 0 comments }

Make Money Make Sense For Your Children

by Magical Penny on October 19, 2017

What is a Junior ISA The sad but simple truth is that we don’t know what the future will hold for our children.
We cannot be the arbiters of their success or failure in life. We can’t make their decisions for them and we can’t insulate them from unfair or unjust things that may happen to them through no fault of their own. All we, as parents, can do is give them the tools, skills and infrastructure to deal with what life throws at them as best they can. This goes for friendships, for relationships, for jobs and careers… And it goes double when it comes to money. We are, at present living in a very uncertain time in the UK. Brexit’s implications on the national economy are only just beginning to be felt and its effect on the labour market, business, GDP and the opportunities that this will have for our children’s financial opportunities will likely take years to be fully realised.

In such a financially turbulent time, it’s never too early (or too late) to start educating your children on all matters monetary to help ensure a stable future for them and their children. While nobody expects your average three year old to understand the complexities of international loans, fiscal multipliers or inflation, there are still a number of ways in which you can encourage them to have a healthy respect for and understanding of money and give them the tools that will enable them to grow into financially responsible adults.

Here are some ways in which you can engender this from a very young age while expanding upon it as your children get older…

ImportantEncourage saving by making it fun

If you’re a very young child, the concept of saving is a tricky sell. Most 2-4 year olds have a vague understanding of money as a commodity but they tend to understand it to be something that’s exchanged for fun stuff like toys and sweets… And kids want toys and sweets. If you start giving your children pocket money from a young age (there’s no ‘right’ time, but the earlier you start, the more opportunity they have to form good financial habits), they’re likely to want to spend their money straight away. The hard part is getting them to understand the benefits of delaying their gratification.

The best way to do this is give them an incentive to save. Get them to focus on something they really want (more than sweets). Explain that you’re not going to buy it for them, but if they can exercise restraint and save their money, you will match their contributions. You can even help them draw a fun chart to help them track how close they are to achieving their goal.

Deal in hard currency

When you think about it, money is quite a nebulous concept. Its value used to be determined by the value of gold but now its value is determined by far more disparate elements. It’s a tricky concept for an adult to understand much less a child, and dealing in contactless payments and Apple Pay can only mystify money further for them. Thus, it’s advisable to deal in cash when buying products in front of your children so that they get a genuine sense of currency lost and its value in relation to the products it buys.

If your young child wants to play ‘shop’, as many do, use this as an opportunity to get them used to handling real money rather than play money.

ConfidenceBe honest about the family finances

As children get owner, the things they want for Christmases and birthdays become more and more expensive and in some cases your household finances may not be conducive to them getting what they want. To a child this is grossly unfair and they’re likely to treat it as an agenda against them personally. You can nip this mentality in the bud by being as open and honest as you can about the family’s finances, delineating in as much detail as you’re both comfortable with where the household income goes every month. This will dispel the odd assumption that children nurture that adults are all infinitely wealthy.

Teach them the importance of budgeting

Budgeting is the most important aspect of any household finances and if children are able to grow into financially independent adults they need to appreciate its importance. This can be gleaned by going over the household budget as above or (better yet) encouraging them to make their own. Even pre-teens can benefit from learning the value of budgeting so that they can prioritise their expenses and assign money to spending and savings accordingly.

{ 0 comments }

house mortgage UKLooking to create a business that has the potential to do well, or invest your money into something you understand?
For some who feel it’s less risky than over options, property can be a good method. It’s something that can be in high demand, and while there are rises and falls in the market it generally appreciates in value over time.

It’s not without its own hassles but here are some of the ways you can make money as a landlord or property investor.


Buy and Sell

There’s a lot of money to be made in flipping houses. Buy a run-down property for cheap, do it up and sell for huge profits. However, there are downsides. First, you really do need to know what you’re doing- many newbies try and fail with this. Many only manage to break even after fees and everything else, some even lose money. You need to have a good team of reliable tradespeople on hand, who you know will do the work quickly, efficiently and for a good price.

You also need to have a good understanding of the property market, things like ceiling prices will affect how much you should spend on a property since you will be limited in the maximum amount you will get back.

But if you do your research, and go about things the right way you could make massive sums of money in a short space of time, giving you chance to move onto the next property. The only issue is you need money up front for the property you’re buying as well as the renovation costs which could run into many thousands. You can borrow small loans from this company if you just need to add the finishing touches, your money will be repaid plus a lot more when you successfully sell up.

house questionBecome a Landlord

If you don’t want to buy and sell, or don’t have money up front to do this then buy to let is a good option. You can take out the mortgage and get tenants in, their rent will pay off your mortgage. In some cases you might be able to make some extra money on top of this too depending on how competitive the rental market is where you live.

By the end will have your house completely paid off for you, allowing you to either sell or continue renting to make a profit. You could even go a step further and invest in a few rental properties, if you can pay for the houses up front you will get money in your bank each month without doing much work at all. In fact, if you have an agent manage them all for you then you won’t even need to deal with tenants problems, viewing, referencing, eviction or anything else.

Buy a Holiday Home

There’s no doubt that purchasing property abroad can be more difficult than in the country where you live. However, there’s the opportunity to earn even more money. If you’re letting to tourists, you can charge a large amount per week- far more than if you were renting out a home. On the plus side, you get to enjoy the property yourself too, saving you money on vacations.


{ 0 comments }